Car Accidents | Duluth, Georgia and Metro Atlanta
Hit by an Uninsured or Underinsured Driver? You Still Have Options.
A crash with a driver who has little or no coverage can leave you facing bills and unanswered questions. Here is how the process typically works and where to start.
By Peter F. Jaraysi · Published November 20, 2026
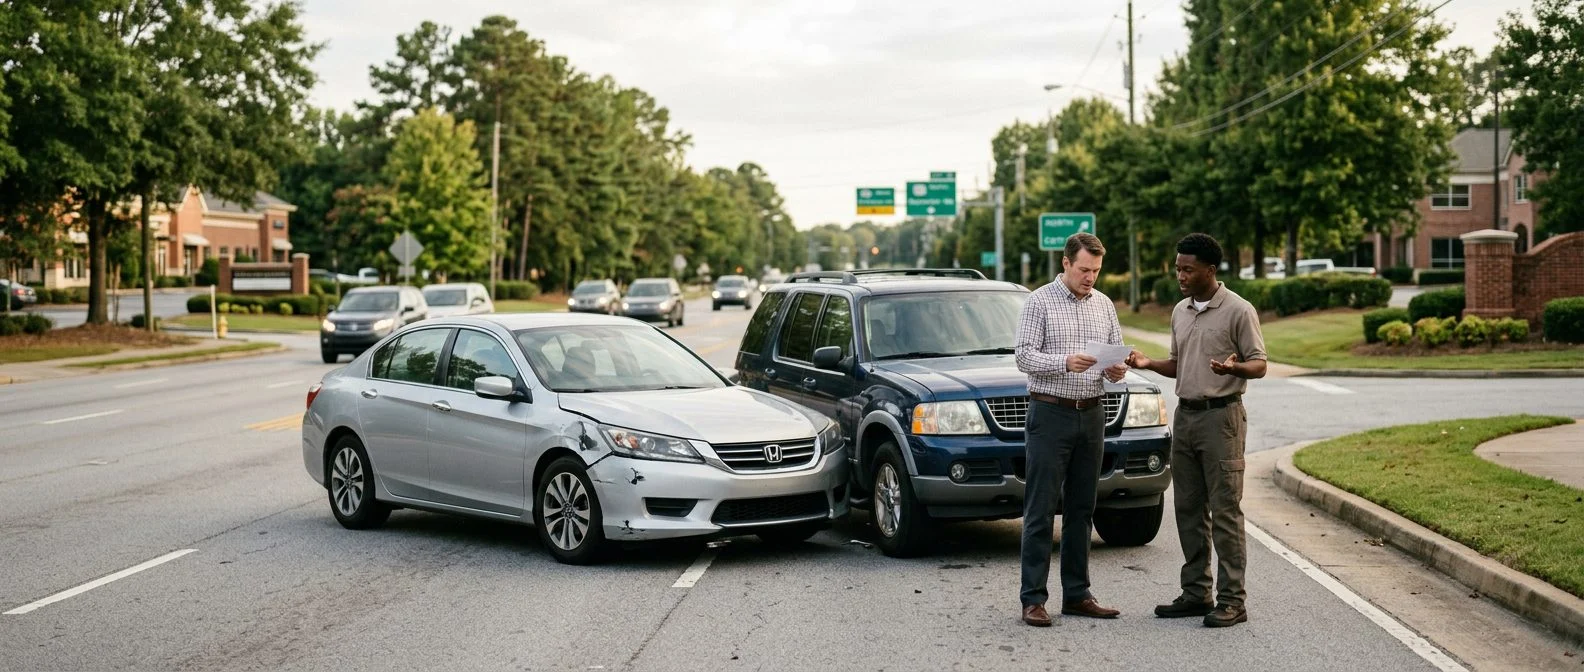
Getting hit by a driver who has no insurance, or not enough, can leave you with bills you did not plan for. In Georgia, your own auto policy may include uninsured or underinsured motorist coverage, and that coverage can help when the at-fault driver cannot pay.
A catastrophic injury, such as a spinal cord injury or a traumatic brain injury, can bring costs and losses that are much larger than a small policy would cover. This guide explains how an uninsured or underinsured driver case works, in plain words, and which Georgia laws apply. For more on the crash itself, see our car accident claims guide.
What Is an Uninsured or Underinsured Driver in Georgia?
An uninsured driver has no liability insurance that applies to the crash. An underinsured driver has some insurance, but the coverage is too low to pay the full losses from the crash.
Georgia’s uninsured motorist statute, O.C.G.A. § 33-7-11, addresses uninsured motorist coverage. It refers to uninsured and underinsured vehicles and sets rules for how your own policy responds.
If a driver with little or no insurance has left you facing a serious injury, our team can review your own policy with you in a free consultation. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
How Your Own Policy Can Pay After a Crash
Under Georgia law, an auto liability policy issued or delivered in this state, on a vehicle principally garaged or principally used in this state, must contain an endorsement or provisions that pay the insured for bodily injury or death caused by an uninsured motor vehicle. The same statute covers the insured’s property damage under the policy. See O.C.G.A. § 33-7-11.
You also make a choice about limits. The statute lets you pick uninsured motorist limits equal to your bodily injury limits, or choose lower limits.
The limits on your policy often decide how much coverage is available. Check the limits on your declarations page before you assume an amount. The facts of the crash also shape how the coverage applies.
Why Catastrophic Injuries Raise the Stakes
Catastrophic injuries often take a long time to understand fully. The Brain Trauma Foundation guidelines say traumatic brain injuries can range from mild to catastrophic. They can cause coma, death, serious long-term problems and heavy medical use.
Paralysis is a serious result of some injuries. MedlinePlus paralysis overview, from the U.S. National Library of Medicine, describes it as loss of muscle function. It can result from spinal cord injuries.
Recovery is hard to predict early. Research on spinal cord injury recovery studies how function returns over time and what affects it. That is one reason the outlook can stay unclear for months after a crash.
Keep every medical record, bill and work note. Records made soon after the crash show what the injury did to your daily life. Our catastrophic injury claims guide covers these injuries in more detail.
How Fault Can Reduce What You Recover
Georgia reduces your damages by your share of fault. If you are 50 percent or more responsible, you cannot receive damages. See O.C.G.A. § 51-12-33.
In Quynn v. Hulsey, the Supreme Court of Georgia applied this 50 percent bar. The jury split fault 50 percent to a truck driver and his employer, and 50 percent to the pedestrian. The estate recovered nothing.
Insurers and other drivers often dispute who caused a crash. The facts of the crash matter a great deal here.
What Are the Deadlines for an Injury Claim?
Most actions for injuries to the person must be brought within two years after the right of action accrues. Loss of consortium claims have a four-year limit. See O.C.G.A. § 9-3-33.
Uninsured cases can have extra timing steps. See O.C.G.A. § 33-7-11.
Do not wait to learn the rules. The time limits keep running while you gather information.
What Happens If the Driver Leaves the Scene?
A driver in a crash that causes injury must stop at the scene. The driver must give a name, address and registration number, exhibit the operator’s license on request if it is available, render reasonable help to the injured person, and, if the injured person is unconscious, appears deceased, or is otherwise unable to communicate, make every reasonable effort to ensure emergency medical services and local law enforcement are contacted. See O.C.G.A. § 40-6-270.
A driver who knowingly fails to stop in a crash that causes death or serious injury faces a felony. The penalty is one to five years of imprisonment. See the same statute.
A driver must also notify police, or the county sheriff or state patrol outside a city, by the quickest means. This applies to crashes causing injury to or death of any person, and to property damage to an apparent extent of $500.00 or more. See O.C.G.A. § 40-6-273.
If the driver is unknown, a claim may name a “John Doe” defendant. See O.C.G.A. § 33-7-11. A police report creates a record of the crash, so ask for the report number at the scene.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Two Kinds of Damages You May Claim
General damages are losses the law presumes flow from a wrong. You can recover them without proving an exact amount. Special damages are losses that actually flow from the wrong. You must prove them. See O.C.G.A. § 51-12-2.
Medical expenses fall under special damages. They are limited to the reasonable value of medically necessary care. If you have health insurance, the evidence can include both the amounts charged and the amounts actually needed to satisfy those charges under your insurance contract. See O.C.G.A. § 51-12-1.1.
How Medicare Reporting Can Affect Medical Bills
Federal law lists liability insurance, including self-insurance, as a plan that must check whether a claimant is entitled to Medicare benefits. See 42 U.S.C. § 1395y(b)(8).
CMS attorney services guidance explains a related rule.
Frequently Asked Questions
What if the driver who hit me has no insurance?
Your own policy may pay under its uninsured motorist coverage. The amount available depends on the limits you chose and the facts of the crash.
How long do I have to file a claim in Georgia?
Most actions for injuries to the person must be brought within two years after the right of action accrues. Loss of consortium claims have a four-year limit.
Can I recover if I was partly at fault?
Yes, but your damages are reduced by your share of fault (O.C.G.A. § 51-12-33; Quynn v. Hulsey (2020)). You cannot recover damages if you are 50 percent or more responsible.
Does Medicare need to know about a crash injury settlement?
Liability insurers must check whether a claimant is entitled to Medicare.
Can I sue a driver I cannot identify in Georgia?
Yes. Georgia law allows an action against an unknown owner or operator named as “John Doe,” and joinder of that party as a defendant is specifically authorized.
Talk With Our Team About Your Coverage
If an uninsured or underinsured driver left you with a serious injury and large bills, you do not have to sort out the policies alone. Our team can review your own policy with you during a free first consultation, so you know what coverage may be available.
La consulta inicial es gratuita, confidencial y sin compromiso de continuar.
Peter F. Jaraysi is the responsible lawyer for this page at Slam Dunk Attorney in Duluth, Georgia. This article gives general information about Georgia law. It is not legal advice about your case. You can reach the firm through its contact page.
How Our Firm Can Help
Plain-Language Answers
We explain your coverage options and the steps ahead in terms you can understand, without legal jargon.
Focused on Protecting Your Claim
Our team works to identify every available source of coverage, including your own policy, and to deal with insurers on your behalf.
Clear Next Steps
We help you organize records, medical documentation and insurance information so you know what to do next.
Compassionate Support
We understand that a crash affects your health, your family and your finances, and we treat your situation with care.
Before You Speak With an Insurer
Do not give a recorded statement or sign any settlement paperwork until you have spoken with a lawyer. Insurance adjusters work for their companies, and early statements can affect your claim.
Steps to Consider After the Crash
Get Medical Care
See a doctor even if your injuries seem minor. Some injuries, such as concussions and soft-tissue damage, can appear days later.
Document the Scene
Take photos of the vehicles, the road, traffic signals and any visible injuries. Write down what you remember while it is fresh.
Collect Insurance Information
Gather the other driver's details, the license plate number and any insurance information they provide, along with the police report number.
Review Your Own Policy
Check whether your policy includes uninsured or underinsured motorist coverage. Your policy language and coverage limits will shape the options available to you.