
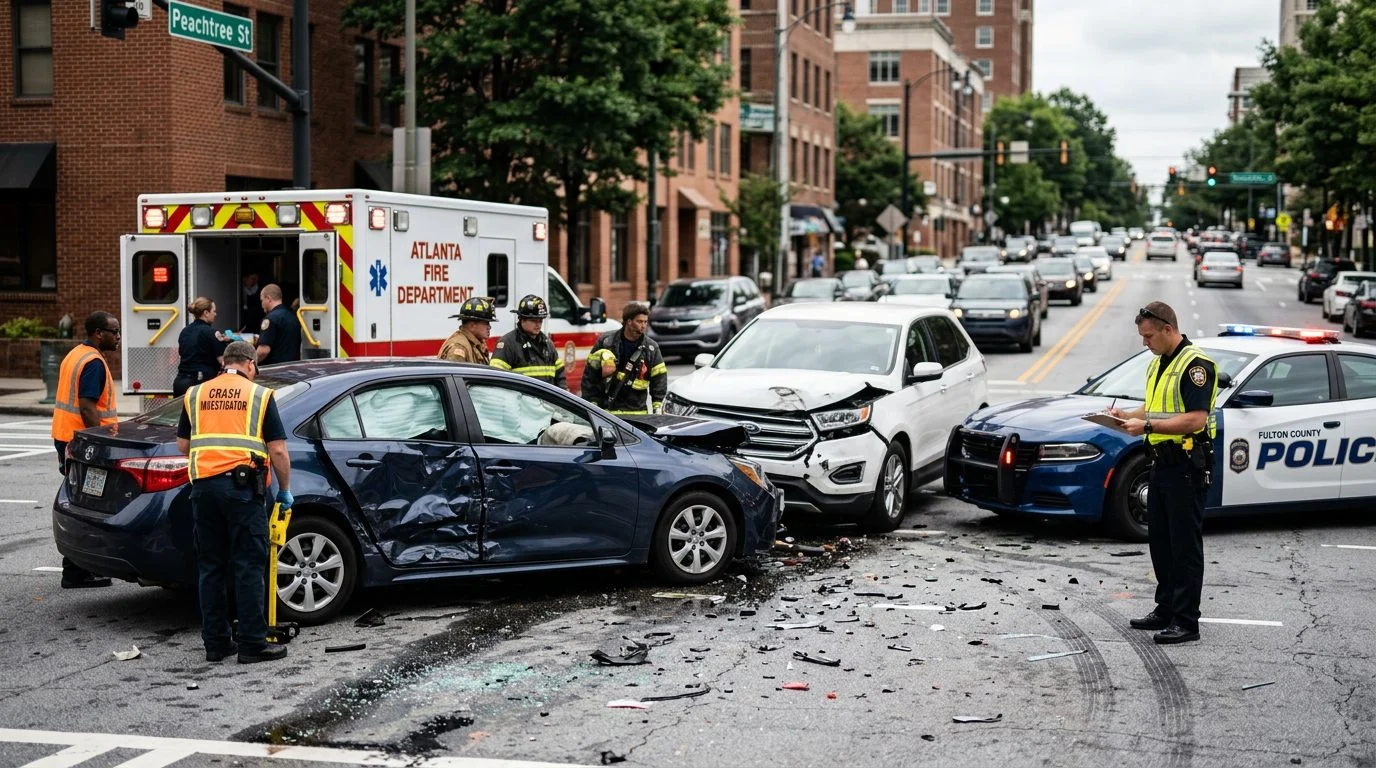
Car Accident Recovery
Who Pays Medical Bills After a Car Accident in Georgia?
Understanding your coverage options and how to get your medical expenses paid.
By Peter F. Jaraysi · Published October 05, 2026
After a car accident in Georgia, medical bills are typically paid by the at-fault driver’s liability insurance, your Medical Payments (Med Pay) coverage, or your Personal Injury Protection (PIP) policy. Which one applies depends on fault, your coverage, and the accident details. Understanding how medical bills get paid after a car accident helps you navigate claims and avoid unexpected costs.
How Medical Bills Get Paid After a Car Accident
Multiple insurance sources may cover your medical costs. If the other driver is clearly at fault, their liability insurance should cover your hospital bills, emergency room visits, and ongoing treatment.
If you’re partially at fault, Georgia’s comparative fault rule may reduce your recovery. You can still recover damages if you’re 49 percent or less responsible for the accident. Your award is reduced by your percentage of fault.
Your own insurance may also pay. Med Pay and PIP coverage pay medical expenses regardless of fault. This is valuable if the at-fault driver is uninsured or if you need immediate payment while a liability claim is investigated.
Hospital emergency departments often work with injured patients on payment plans while claims are pending. Don’t ignore bills or skip communication with providers.
If you're facing mounting medical bills after a car accident in Georgia and aren't sure which insurance should cover them, reach out to discuss your situation and what options may be available. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Medical Payments Coverage: What It Covers
Medical Payments (Med Pay) coverage is optional insurance that pays medical bills for you and your passengers after an accident. It pays regardless of who caused the crash.
Most Med Pay policies cover reasonable and necessary medical expenses. These include hospital stays, emergency room visits, surgery, rehabilitation, and ongoing treatment related to the accident. Policy limits vary, and you can often choose higher limits when you purchase your policy.
Med Pay does not cover lost wages, vehicle repairs, or pain and suffering. It’s designed to handle immediate medical costs quickly, without waiting for a liability determination.
If you have Med Pay and the other driver is at fault, you can file a claim with your own insurance first. This covers medical bills. Then pursue the at-fault driver’s liability insurance for additional damages like pain and suffering or lost income.
Personal Injury Protection (PIP) in Georgia
Georgia allows optional Personal Injury Protection (PIP) coverage on auto policies. PIP is broader than Med Pay. It covers medical expenses and lost wages for you and your passengers. PIP pays benefits regardless of fault.
Like Med Pay, PIP pays regardless of who caused the accident. This makes it especially valuable if you’re hit by an uninsured driver.
PIP covers reasonable and necessary medical treatment related to the accident. Some PIP policies also include funeral expense coverage, which matters if the accident is fatal. Limits and deductibles vary by policy. Review your declarations page to understand your coverage.
If you don’t have PIP and the other driver is uninsured, you’ll rely on your Med Pay (if you have it) or pursue the uninsured driver directly. The direct approach is more difficult and time-consuming.
When the Other Driver’s Insurance Pays
If the other driver is clearly at fault, their liability insurance is responsible for your medical bills. File a claim with their insurance company. Provide the accident report, your medical records, and itemized bills.
The insurance company will investigate the accident and determine liability. If liability is clear, they may authorize treatment directly with providers. Or they may reimburse you after you pay upfront, depending on the claim process.
Insurance companies sometimes dispute liability or delay payment while investigating. If the claim is straightforward, payment may come within weeks. If it’s contested, the process can take months.
Keep all medical records, bills, and receipts. Don’t accept a settlement offer without understanding what it covers. Once you settle, you generally can’t pursue additional claims for that accident.
What Happens When the Other Driver Is Uninsured or Underinsured
Uninsured motorist (UM) coverage protects you if the at-fault driver has no insurance. Underinsured motorist (UIM) coverage applies when their liability limits don’t cover all your bills. For example, if they have $25,000 in liability coverage but your medical bills total $50,000, your UM/UIM coverage can pay medical bills and other damages up to your policy limit.
These coverages are optional in Georgia but strongly recommended. This is especially true if you live in an urban area where uninsured drivers are common.
Without UM/UIM coverage, you may have to pursue the uninsured driver directly in court. This is a costly and uncertain process. If you don’t have these coverages and are hit by an uninsured driver, your only option may be to sue the driver personally. This is difficult if they have few assets.
Learn more about uninsured motorist coverage and how it protects you.
Hospital Bills and Emergency Room Costs
Emergency room visits and hospital stays generate substantial bills quickly. A single ER visit can cost thousands of dollars. Hospital stays can run into tens of thousands of dollars.
Medical Payment coverage and PIP typically cover emergency treatment immediately. They don’t wait for fault to be determined. This is crucial because hospitals won’t delay care while you sort out insurance.
After you’re treated, hospital billing departments can sometimes work with you on payment plans. Call the hospital’s billing office and explain your situation. Many will hold off on collection action if you’re actively pursuing an insurance claim.
Keep all medical records and itemized bills for your insurance claim or potential legal action. Don’t throw away any billing statements, even if they seem confusing. They’re evidence of your damages.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Funeral Expenses After a Fatal Car Accident
Funeral and burial costs add financial burden to an already devastating loss. Some PIP policies include funeral expense coverage as part of the benefit.
If the other driver is at fault, their liability insurance may cover funeral expenses as part of your damages claim. In a wrongful death claim, funeral and burial costs are recoverable damages that a jury or settlement can address.
Family members should preserve all funeral expense receipts, invoices, and documentation. These are essential evidence if you pursue a wrongful death claim. An attorney can help you identify all available sources of coverage and ensure funeral costs are included in any settlement.
Passenger Coverage: Who Pays for Injured Passengers
Passengers injured in a car accident may be covered by multiple insurance sources. The at-fault driver’s liability insurance covers passenger injuries. The vehicle owner’s Med Pay or PIP coverage typically covers passengers as well.
This means a passenger can file claims against either driver’s insurance, depending on who caused the accident.
Passengers have the right to pursue their own claims. They are not limited to the driver’s coverage alone. If you’re a passenger injured in someone else’s vehicle, you can file a claim with the vehicle owner’s insurance for Med Pay or PIP benefits. Then pursue the at-fault driver’s liability insurance for additional damages.
Don’t assume the driver will handle your claim. Protect your own interests by reporting the accident to your own insurance and documenting your injuries.
Steps to Take When Medical Bills Arrive
Report the accident to your insurance company promptly, ideally within 24 hours. Provide copies of the accident report, police report (if available), medical bills, and medical records to your insurer.
Keep detailed records of all medical treatment, appointments, prescriptions, and expenses. Don’t ignore bills or collection notices. Communicate with providers and insurers about your claim status.
Ask your insurance company about the claims process and expected timeline. Request a claim number and the name of your adjuster so you can follow up.
If bills are substantial or coverage is unclear, consider consulting an attorney early. Many injury attorneys offer free case reviews. They can help you understand your coverage and identify all available sources of payment.
When Insurance Doesn’t Cover All Your Medical Costs
Medical bills may exceed available insurance coverage. If the at-fault driver’s liability limits are low and your bills are high, you may have a right to pursue additional compensation through a personal injury claim.
An attorney can help evaluate whether the at-fault driver’s assets, additional insurance policies, or umbrella coverage apply to your case.
Unpaid medical bills can sometimes be negotiated or included in a settlement. Some healthcare providers will reduce bills or agree to wait for settlement proceeds before pursuing collection. An attorney can negotiate on your behalf and ensure all available coverage sources are exhausted before you pay out of pocket.
Getting Help Understanding Your Coverage and Bills
Your insurance agent can explain your specific coverage limits and what is covered under your policy. Medical providers’ billing departments can answer questions about charges and may offer payment plans.
An attorney can review your insurance policies, medical bills, and the accident details. They can identify all available coverage sources and advise you on next steps.
Legal guidance is especially important if bills are high, coverage is unclear, or the insurance company denies your claim. Consider reaching out to discuss your Georgia car accident claims and your options.
If you're facing mounting medical bills after a car accident in Georgia and aren't sure which insurance should cover them, reach out to discuss your situation and what options may be available. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Frequently Asked Questions
What’s the difference between Med Pay and PIP coverage in Georgia?
Med Pay covers medical expenses only, regardless of fault. PIP covers medical expenses and lost wages, also regardless of fault. PIP is broader, but both are optional in Georgia.
Can I file a claim with both the at-fault driver’s insurance and my own Med Pay?
Yes. You can use your Med Pay to cover immediate bills. Then pursue the at-fault driver’s liability insurance for additional damages like pain and suffering.
What if the other driver’s insurance denies my claim?
If liability is disputed or the claim is denied, you may have grounds to appeal or pursue a personal injury lawsuit. An attorney can review the denial and advise you on your options.
How long does it take for insurance to pay medical bills?
Simple claims may be paid within weeks. Disputed claims can take months. Always ask your adjuster for an expected timeline.
Can I recover funeral expenses if a loved one dies in a car accident?
Yes, funeral and burial costs are recoverable damages in a wrongful death claim if the other driver is at fault. Some PIP policies also cover funeral expenses.
If you’re navigating medical bills after a car accident in Georgia and aren’t sure which insurance should cover them or whether you have a claim for damages beyond what insurance will pay, our team can review your situation and explain your options. Contact us for a free case review.
Your Coverage Options in Georgia
Medical Payments (Med Pay)
Covers your medical bills regardless of who caused the accident. It's optional coverage you can add to your own policy. Med Pay typically covers reasonable and necessary medical expenses up to your policy limit.
Personal Injury Protection (PIP)
Broader than Med Pay—covers medical expenses and lost wages if you can't work. PIP also pays regardless of fault. Like Med Pay, it's optional in Georgia and applies to your own policy.
At-Fault Driver's Liability Insurance
If the other driver caused the accident, their liability insurance may cover your medical bills. This is often the primary source of recovery, but claims can take time to process and may require negotiation.
Your Health Insurance
Your own health insurance can pay medical bills after a car accident. However, your health insurer may have a right to be reimbursed from any settlement or judgment you receive.
Important: Coordination of Benefits
You may be able to use multiple coverage sources—for example, your Med Pay and the at-fault driver's liability insurance. However, the goal is full compensation, not double recovery. If you receive payment from one source, it may reduce what you can claim from another. Understanding how your policies work together is crucial.
How Slam Dunk Attorney Can Help
Review Your Coverage
We examine your insurance policies and the at-fault driver's coverage to identify all available sources of payment for your medical bills.
Handle Insurance Claims
We communicate with insurers on your behalf, file claims promptly, and work to resolve payment disputes so you can focus on recovery.
Protect Your Rights
We ensure insurers don't undervalue your claim or deny payment improperly. If negotiation doesn't work, we're prepared to pursue your case further.
Explain Your Options
In plain language, we walk you through what each coverage option means for your situation and what to expect at each step.