
Navigate Your Georgia Car Accident Insurance Claim
Understand the process, timeline, and next steps after a crash. Slam Dunk Attorney guides you through every stage.
By Peter F. Jaraysi · Published September 28, 2026
Georgia Car Accident Insurance Claim: Process & Timeline
After a car accident in Georgia, filing an insurance claim recovers money for vehicle damage, medical bills, and lost wages. The process involves reporting the accident, working with a claims adjuster, proving liability, and negotiating a settlement. Understanding each step helps you avoid costly mistakes and protect your rights.
If you've filed a claim and the settlement offer feels too low, or liability is being disputed, reach out—people in your situation contact us regularly to review their claim. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
What Is a Car Insurance Claim After an Accident in Georgia?
A car insurance claim is a formal request to an insurance company to pay for damages and injuries caused by a car accident. In Georgia, a fault-based state, the at-fault driver’s insurer is responsible for damages. You can also file with your own insurer under certain coverages. You typically file a claim as the injured driver or vehicle owner. Passengers and pedestrians can also file. Claims cover property damage, medical expenses, lost income, and pain and suffering.
What Does a Car Insurance Claim Cover in Georgia?
Coverage depends on the type of insurance you carry. Here’s what each covers:
Liability coverage (required in Georgia): Pays for injuries and property damage you cause to others. This includes medical bills, vehicle repair, and lost income. This protects you if you’re at fault.
Collision coverage (optional): Covers damage to your vehicle regardless of who caused the accident. You pay a deductible, and the insurer covers the rest.
Comprehensive coverage (optional): Covers non-collision damage like theft, weather, vandalism, or hitting an animal.
Uninsured/underinsured motorist coverage (optional but recommended): Protects you if the at-fault driver has no insurance or insufficient coverage. This is critical in Georgia, where many drivers are uninsured. Learn more about uninsured motorist claims.
Medical payments coverage (optional): Covers medical expenses for you and passengers, regardless of fault. No need to prove liability.
What is NOT covered: Punitive damages, traffic tickets, rental car costs (unless you have rental reimbursement), or claims from illegal activity.
Step-by-Step: How the Insurance Claim Process Works in Georgia
The claim process follows a predictable path. Here’s what happens at each stage:
Step 1 – Report the accident immediately
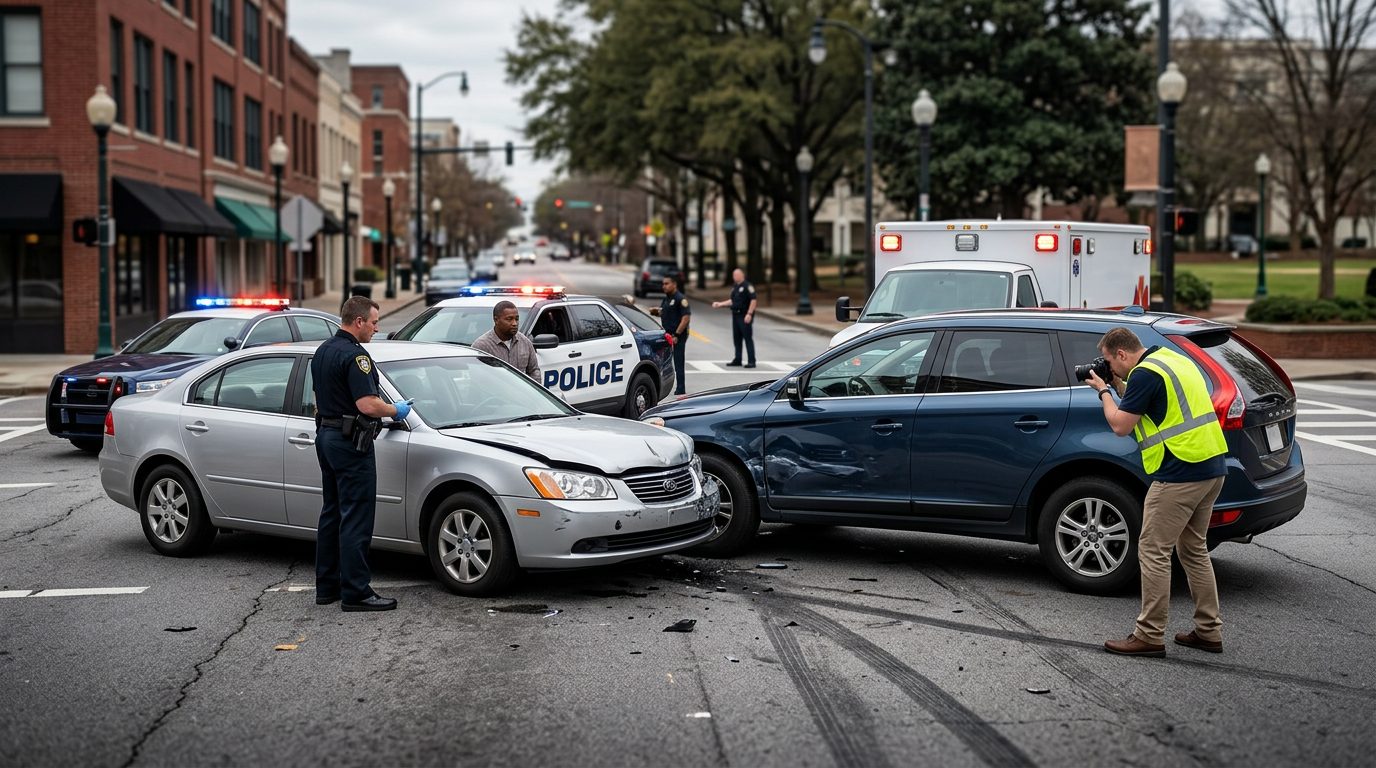
Call police if there’s injury or significant damage (required in Georgia). Get the police report number. Exchange information with the other driver(s)—name, phone, address, insurance company, policy number, and vehicle details. Take photos of the accident scene, vehicle damage, road conditions, and any visible injuries. Write down what happened while it’s fresh.
Step 2 – Notify your insurer
Contact your insurance company within 24–48 hours. Provide the accident details, police report number, and contact information for other parties. Be honest but careful. Do not admit fault or speculate about the cause. Stick to facts—date, time, location, what you were doing, what happened.
Step 3 – Insurer assigns a claims adjuster
The adjuster investigates the accident and reviews the police report. They inspect vehicle damage and gather statements from you, the other driver, and witnesses. They determine who was at fault and whether the claim is covered.
Step 4 – Medical evaluation and documentation
Seek medical treatment promptly, even if you feel fine. Injuries can appear hours or days later. Keep all medical records, bills, receipts, and documentation of treatment. Provide these to your insurer. The more complete your medical file, the stronger your claim.
Step 5 – Insurer determines liability
Using the police report, witness statements, and evidence, the adjuster decides who was at fault. Georgia’s comparative fault system allows you to recover even if partially at fault. You can recover as long as you’re less than 50% responsible. This is where disputes often arise.
Step 6 – Damage assessment and repair estimate
The adjuster estimates repair costs or determines whether your vehicle is a total loss. A total loss usually occurs when repair costs exceed 70–80% of the vehicle’s value. You have the right to obtain a second estimate from another repair shop. Submit it to the insurer.
Step 7 – Settlement offer or denial
The insurer makes an offer based on coverage limits, damages, and liability. You can accept, negotiate, or reject. Do not sign anything without reading it carefully.
Step 8 – Resolution
Once you agree, the claim is paid within 5–10 business days. If you reject the offer or the insurer denies the claim, you may pursue negotiation or legal action.
Timeline: How Long Does a Car Insurance Claim Take in Georgia?
Most straightforward claims settle in 2–4 months. Complex cases take longer.
- Immediate (0–2 days): Report the accident to police and your insurer.
- Early investigation (3–14 days): Adjuster contacts you, requests documents, begins liability review.
- Medical and damage phase (2–8 weeks): Medical treatment continues, repair estimates are obtained, adjuster gathers evidence.
- Liability determination (4–12 weeks): Insurer decides fault and coverage; may request additional information.
- Settlement negotiation (1–4 weeks or longer): Insurer makes an offer; you review and respond; negotiation may occur.
- Payment (5–10 business days after settlement): Funds are issued once you agree and sign paperwork.
Disputed liability, serious injuries, or multiple vehicles can extend timelines to 6–12 months or longer.
Georgia’s Comparative Fault Rule and Your Claim
Georgia’s comparative fault rule is critical to your claim value. Under O.C.G.A. § 51-12-33, you can recover damages even if you are partially at fault. You must be less than 50% responsible for the accident.
Here’s how it works: If you are 20% at fault and damages total $10,000, you recover $8,000 (80% of damages). The adjuster will argue your percentage of fault to minimize their payout. Even a small difference in fault percentage can mean thousands of dollars in your recovery. This is where disputes often arise. Learn more about Georgia’s comparative fault law.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Common Reasons Insurance Claims Are Delayed or Denied
Understanding why insurers delay or deny claims helps you avoid these pitfalls:
- Insufficient evidence of liability: Unclear who was at fault; conflicting witness statements.
- Policy exclusions or coverage gaps: You lack the coverage type needed (e.g., no uninsured motorist coverage if hit by an uninsured driver).
- Lapsed or invalid policy: Your insurance was not active at the time of the accident.
- Failure to report promptly: Delayed notification gives insurers grounds to deny or reduce payment.
- Pre-existing condition disputes: Insurer claims injuries were not caused by the accident.
- Exceeding policy limits: Damages exceed your coverage; you may pursue the at-fault driver directly.
- Fraud concerns: Insurer suspects misrepresentation or a staged accident (rare but serious).
If your claim is denied, we can help you understand your options. Learn more about insurance claim denials.
What You Should Do (and Not Do) During the Claim Process
Your actions after an accident directly affect your claim. Here’s what matters:
DO: – Seek medical attention immediately, even if you feel fine. – Keep all receipts and records—medical bills, repair estimates, lost wage documentation. – Document the accident scene with photos and video. – Report to police and your insurer promptly (within 24–48 hours). – Be honest and consistent in all statements.
DO NOT: – Admit fault or apologize at the scene. – Sign anything without reading it carefully. – Post about the accident on social media (insurers monitor this). – Accept the first settlement offer without review. – Communicate with the other driver’s insurer without legal guidance. – Delay medical treatment to avoid appearing greedy (insurers use this against you).
Document everything. Medical bills, repair estimates, lost wage records, correspondence with insurers, and photos of damage and injuries all strengthen your claim.
When You Need Legal Help with Your Insurance Claim
Many claims settle without an attorney, but legal help matters when:
- Liability is disputed: The other driver or their insurer contests fault, or the accident is complex (multi-vehicle, unclear circumstances).
- Your injuries are serious: Significant medical bills, ongoing treatment, or long-term effects; insurers often undervalue these claims.
- The settlement offer seems too low: The adjuster’s valuation doesn’t match your actual damages or medical costs.
- You are partially at fault: Georgia’s comparative fault rule applies; an attorney can argue your percentage down to maximize recovery.
- The insurer denies your claim: You believe the denial is unjustified and want to appeal or pursue legal action.
- Policy limits are exceeded: Damages exceed your coverage; you may need to pursue the at-fault driver’s assets or insurance.
- You are dealing with an uninsured or underinsured driver: Your own uninsured/underinsured motorist coverage may require legal interpretation.
Frequently Asked Questions
Q: Do I have to file a claim with my own insurer, or can I go straight to the at-fault driver’s insurer?
You can file with either, but filing with your own insurer first is often safer. They have a duty to defend you and will handle the claim. Filing with the at-fault driver’s insurer directly may limit your options.
Q: What if the other driver doesn’t have insurance?
If you have uninsured motorist coverage, your own insurer will cover your damages up to your policy limit. If you don’t, you may pursue the at-fault driver directly in court. Recovery may be difficult.
Q: Can the insurance company force me to use their repair shop?
No. You have the right to choose your own repair facility. The insurer must pay for repairs that restore your vehicle to pre-accident condition.
Q: How is pain and suffering calculated in Georgia?
There’s no fixed formula, and Georgia law does not prescribe any particular method for valuing pain and suffering. Some people and insurers use informal approaches to discuss it—such as applying a multiplier to medical bills or a per-diem method (a daily rate over the days of recovery)—but these are not established Georgia methodology and do not indicate any expected recovery. Pain and suffering depends on the specific facts of each case.
Q: What if I disagree with the adjuster’s damage estimate?
Obtain a second estimate from another repair shop and submit it to the insurer. If estimates differ significantly, the insurer may agree to a compromise or authorize additional inspection.
Q: How long do I have to file a claim in Georgia?
There’s no strict deadline to file a claim, but report the accident to your insurer within 24–48 hours. Georgia’s statute of limitations for personal injury lawsuits is two years from the date of the accident.
Q: Will filing a claim raise my insurance rates?
Not necessarily. If you’re not at fault, most insurers won’t raise your rates. If you’re at fault, rates may increase, depending on the insurer and policy.
Why Slam Dunk Attorney Helps with Car Insurance Claims
We handle car accident claims across metro Atlanta and Georgia. We know Georgia’s comparative fault rules and insurance regulations. We understand how local insurers operate.
We’ve handled hundreds of car accident claims. We know how to identify undervalued settlements and push back on denials. We work on contingency for personal injury claims—you pay nothing unless we recover for you. You may owe case costs;
The Car Accident Claim Process
Step 1: Report the Accident
Notify your insurance company as soon as possible. Provide details about the crash, the other driver, and any injuries. Document the scene with photos if safe to do so.
Step 2: Investigation & Assessment
Your insurer will assign an adjuster to investigate the claim. They'll review police reports, medical records, repair estimates, and witness statements to determine liability and damages.
Step 3: Negotiation & Settlement
The adjuster will make an offer based on their findings. You can accept, negotiate, or reject the offer. This phase typically takes weeks to months depending on claim complexity.
Step 4: Resolution
Once settled, the insurer issues payment for approved damages. If disputes arise, you may need legal representation to protect your rights.
Filing Your Claim: Your Options
You can file a claim with your own insurance company or directly with the at-fault driver's insurer. Filing with your own insurer first is often the safer approach—they have a duty to handle your claim fairly. If you file directly with the other driver's insurer, you may have fewer protections and options.
What You Should Know
Timeline Varies
Simple claims may resolve in weeks; complex cases can take months. Factors include injury severity, liability disputes, and insurance company responsiveness.
Documentation Matters
Keep all records: police reports, medical bills, repair estimates, photos, and correspondence with insurers. These strengthen your claim and protect your interests.
Uninsured Drivers
If the other driver lacks insurance, your own uninsured motorist coverage may apply. Your insurer can explain your options under your policy.
Disputes Happen
If the insurer denies your claim or offers too little, you don't have to accept. Legal representation can help you challenge unfair decisions and pursue fair compensation.
When to Seek Legal Help
If you've suffered serious injuries, the claim is being denied, or you're unsure about an offer, don't navigate alone. An attorney can review your case, communicate with insurers on your behalf, and protect your rights throughout the process.