

Car Accidents | Alpharetta
Leased Car Accident Without Insurance
You can still be held personally liable—even in a leased vehicle. Slam Dunk Attorney helps Alpharetta residents understand their options and protect their future.
By Peter F. Jaraysi · Published October 05, 2026
Leased Car Accident with No Insurance in Alpharetta: What Happens Next
If you were in a car accident while driving a leased vehicle and don’t have adequate insurance coverage, you face serious financial and legal consequences. The lessor, the other driver, and Georgia law all have claims against you—and without insurance to defend you, your personal assets are at risk.
Here’s what you need to know about liability, what you owe, and how to protect yourself.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
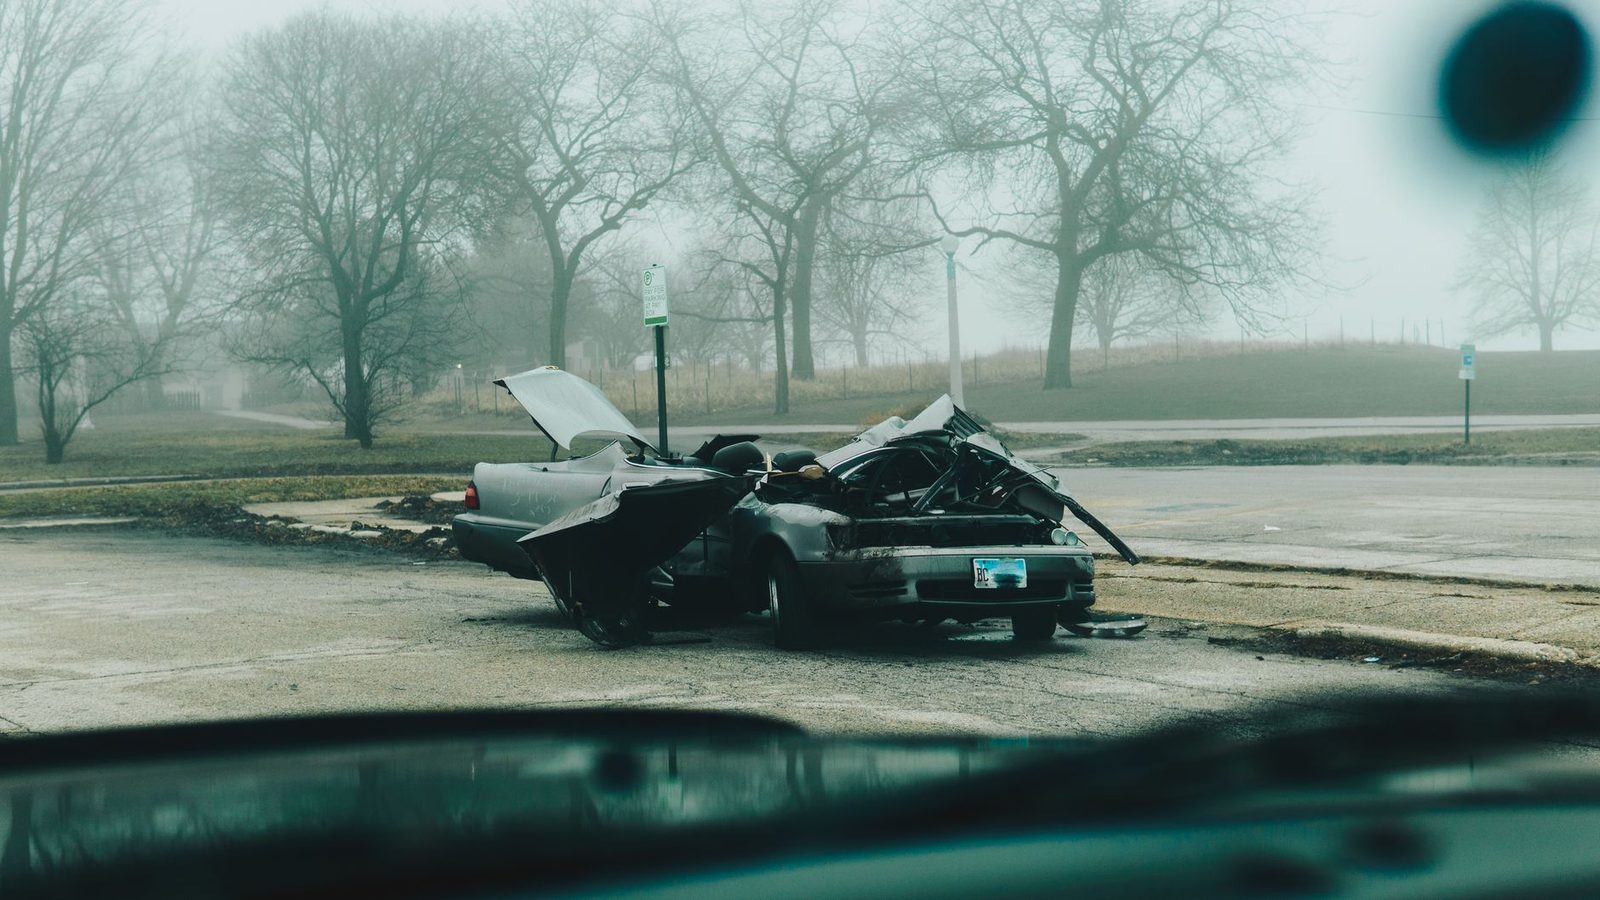
What Happens When You’re in a Leased Car Accident Without Adequate Insurance
When you lack required insurance on a leased vehicle, you become personally liable for all damage to the car, injuries to others, and property damage caused by the accident. Lease agreements require comprehensive and collision coverage at minimum, in addition to Georgia’s mandatory liability insurance of $25,000 per person and $50,000 per accident for bodily injury, plus $25,000 for property damage.
Without that coverage, you have no insurer to pay your legal defense or any judgment against you. Your wages can be garnished, your bank accounts levied, and your credit damaged. The lessor—the finance company that owns the vehicle—also has a financial interest in the car and may pursue you directly for uninsured losses through a process called subrogation (recovery from the at-fault party’s insurer).
Driving a leased car without required insurance also violates Georgia law. You face criminal penalties including fines, license suspension, and potential jail time. The lessor can declare you in breach of the lease and repossess the vehicle.
Who Pays for Damage on a Leased Car After an Accident?
The answer depends on who caused the accident and what insurance you have.
If you are at fault and lack collision coverage: You typically pay for repairs or the vehicle’s total loss value out of pocket. If the vehicle is totaled, you may owe the lessor the difference between what the car is worth and what you still owe on the lease—called a deficiency balance. This can be thousands of dollars.
If the other driver is at fault: Their liability insurance should cover damage to the leased vehicle, your injuries, and other losses. However, you must file a claim and prove the other driver’s liability. Georgia follows modified comparative fault, meaning damages are reduced by your percentage of fault, and if you are 50 percent or more responsible, you recover nothing.
The lessor’s role: The lessor may file a claim against the at-fault driver’s insurer to protect its financial interest in the vehicle. The lessor may also pursue you for any shortfall if the insurance payout is less than the damage or lease balance.
Gap insurance: If you have gap insurance, it covers the difference between the vehicle’s actual cash value and what you owe on the lease if the car is totaled. Without it, you are responsible for the gap—even if the accident was not your fault.
What Happens If You Don’t Have Insurance on a Leased Vehicle?
Driving uninsured on a leased car creates multiple legal and financial crises.
You remain personally liable for all damages, medical bills, and third-party claims—with no insurer to defend you. If someone is injured, they can sue you directly. If a judgment is entered against you, creditors can garnish your wages, levy your bank accounts, and damage your credit rating for years.
The lessor can breach the lease and repossess the vehicle. You may still owe the remaining balance on the lease even after repossession.
If you hit another vehicle or property, the owner can sue you personally. Without insurance, you have no legal defense and must pay all costs and damages yourself.
My Leased Car Was Totaled. What Should I Do Now?
If your leased car is totaled in an accident, act quickly to protect your rights and minimize your liability.
Immediately after the accident: – Stop and document the scene with photos of vehicle damage, road conditions, other vehicles, and weather. – Collect contact information from witnesses. – Call police and obtain a crash report number; this is critical evidence. – Do not admit fault or sign anything without understanding the implications.
Within hours: – Seek medical attention if you or passengers are injured; document all injuries and treatment. – Notify your insurance company, even if you believe you lack coverage—they need to know about the accident. – Notify the lessor immediately; they have a right to know about damage to their asset.
Within days: – Gather evidence: repair estimates, medical records, lost wages, photographs, and any communications with the other driver or their insurer. – Do not settle with the other driver’s insurer without understanding the full extent of your injuries and damages. – Contact a car accident lawyer before signing any release or settlement agreement.
A lawyer can help you pursue a claim against the at-fault driver’s insurance, negotiate with the lessor, and protect you from personal liability.
Can You Return a Leased Car After an Accident?
Most lease agreements require you to return the vehicle in good condition, normal wear and tear excepted. If the car is damaged from an accident, you cannot simply return it.
If the vehicle is totaled, the lease ends, but you may owe a deficiency if the insurance payout is less than the remaining lease balance. Gap insurance protects you from this shortfall, but only if you have it.
If the other driver is at fault, their insurer may pay the lessor directly for the vehicle’s value. However, you must ensure the claim is filed and pursued. If the payout falls short, you may still owe the lessor the difference—unless gap insurance covers it.
Early termination of the lease due to an accident may also trigger early-termination fees in addition to damage liability.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Understanding Insurance Requirements for Leased Cars in Georgia
Georgia law requires all drivers to carry minimum liability insurance. Under O.C.G.A. § 40-6-270 (Keais v. Kelley (2026)), the minimum is $25,000 per person and $50,000 per accident for bodily injury, and $25,000 for property damage.
Lease agreements typically require higher limits and mandate comprehensive and collision coverage. Comprehensive coverage pays for theft, weather, and vandalism. Collision coverage pays for accidents. Uninsured/underinsured motorist coverage protects you if hit by a driver without adequate insurance.
Gap insurance is optional but highly recommended for leased vehicles. It covers the gap between what you owe on the lease and the vehicle’s actual cash value if the car is totaled—potentially saving you thousands of dollars.
If you cannot afford required coverage, you cannot legally lease a car in Georgia.
What If the Other Driver Was at Fault?
If the other driver caused the accident, their liability insurance should cover your damages and injuries. You have the right to file a claim for vehicle damage, medical expenses, lost wages, and pain and suffering.
The at-fault driver’s insurer may also pay the lessor directly for damage to the leased vehicle. However, you should not settle with their insurer without understanding the full extent of your injuries and damages. A lawyer can help you pursue a complete claim and ensure you are fully compensated, especially if your own insurance is inadequate.
Georgia is a fault-based state, meaning the at-fault party is responsible for damages. You do not need to prove negligence beyond a preponderance of the evidence—the more likely than not standard.
How Slam Dunk Attorney Helps After a Leased Car Accident in Alpharetta
We represent Alpharetta residents and others across metro Atlanta who have been injured in car accidents, including those driving leased vehicles with insurance gaps. We investigate the accident, gather evidence, and determine liability so you understand who is responsible and what your options are.
We handle all communication with insurance companies, the lessor, and the at-fault party’s insurer on your behalf. We pursue claims for vehicle damage, medical bills, lost wages, and other losses you have suffered. We explain your rights and options in plain language so you can make informed decisions about your case.
We work on a contingency basis: you pay no attorney fee unless we recover compensation for you. You may still be responsible for court costs and case expenses. We are based in Duluth, Georgia, and serve all of metro Atlanta, including Alpharetta, Johns Creek, Marietta, and surrounding areas.
Frequently Asked Questions
Can I be sued personally if I’m in an accident while leasing a car?
Yes. If you are found liable, the injured party can sue you personally, and a judgment can result in wage garnishment, bank levies, and a damaged credit rating.
What if I can’t afford to pay the lessor for damage to the leased car?
You may still be liable. A lawyer can help you pursue a claim against the at-fault driver’s insurance to cover the damage and protect you from personal liability.
Do I need to tell my lease company about the accident?
Yes. Your lease agreement requires you to notify the lessor of any damage. Failure to do so can be a breach of the lease and grounds for repossession.
Can the lessor sue me for damage to the leased car?
Yes, if you are at fault and lack insurance to cover the damage, the lessor can pursue you for the loss.
What is gap insurance, and do I need it?
Gap insurance covers the difference between what you owe on the lease and the vehicle’s actual cash value if it’s totaled. It is optional but highly recommended.
How long do I have to file a claim after an accident?
Georgia law generally allows two years from the date of injury to file a lawsuit, but you should act quickly to preserve evidence and file insurance claims promptly.
What should I do if the other driver’s insurance denies my claim?
Contact a lawyer. We can investigate the denial, appeal it, or pursue a lawsuit if necessary to recover what you are owed.
If you were in a leased car accident in Alpharetta and are unsure about your insurance coverage, liability, or what you owe the lessor, you may have options to recover compensation from the at-fault driver. Call Slam Dunk Attorney for a free case review and learn what your rights are. There is no obligation, and all conversations are confidential.
Personal Liability Doesn't Stop at the Lease
If you cause an accident in a leased car and lack insurance coverage, an injured party can sue you personally. A judgment can lead to wage garnishment, bank levies, and credit damage. This is why immediate legal guidance matters.
What Happens After a Leased Car Accident
You May Face Personal Liability
Without insurance, you're personally responsible for injuries and damages. The lessor may also hold you liable for harm to the vehicle itself.
The Lessor's Interests Complicate Things
Your lease agreement typically requires you to maintain coverage. Damage claims from the lessor can pile on top of injury claims from the other party.
Your Rights Still Matter
Even without insurance, you may have defenses or counterclaims. A lawyer can help identify whether the other driver shares fault or acted negligently.
Time Is Critical
Evidence disappears, witnesses move, and legal deadlines apply. Early action protects your position and preserves your options.
How Slam Dunk Attorney Can Help
Protect Your Personal Assets
We help you understand your exposure and explore ways to minimize personal liability in the accident claim.
Navigate Lease & Insurance Issues
Lease terms, lessor claims, and coverage gaps create complexity. We clarify what you owe and what you may not.
Handle Communication with All Parties
We communicate with the other driver's insurer, the lessor, and any injured parties on your behalf.
Identify Your Options
Whether the other driver was at fault, partially at fault, or you share responsibility, we explain your path forward.