
Truck Accident Claims
Navigate Your Truck Accident Insurance Claim in Georgia
A clear roadmap for filing, negotiating, and protecting your right to fair compensation after a serious truck collision.
By Peter F. Jaraysi · Published September 28, 2026
How Insurance Claims Work After a Truck Accident in Georgia: A Step-by-Step Guide
After a truck accident in Georgia, the insurance claims process is your primary path to recovering medical bills, lost wages, vehicle damage, and other costs. Understanding how it works—from the moment you report the accident through settlement—helps you protect your rights and avoid common mistakes that delay or reduce payouts.
Truck accidents are often more complex than passenger-vehicle collisions. The size and weight of commercial trucks mean injuries tend to be more severe and property damage more extensive. Georgia law requires drivers to carry minimum liability insurance, and knowing how that coverage works protects you whether you’re the injured party or the at-fault driver.
If you've been injured in a truck accident and the insurance process feels overwhelming, we help people in your situation understand their options and protect their rights—reach out for a free case review. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Why the Insurance Claim Process Matters After a Truck Accident
The insurance claim process is the mechanism through which you recover the financial costs of the accident. Without understanding how it works, you risk accepting unfair settlement offers, missing deadlines, or inadvertently saying something that weakens your claim.
Truck accidents often result in serious injuries and substantial medical expenses. A single hospitalization, surgery, or months of physical therapy can cost tens of thousands of dollars. Lost wages add up quickly if you’re unable to work during recovery. Vehicle repair or replacement is another major expense. Insurance is designed to cover these costs—but only if you navigate the process correctly.
Georgia law requires insurers to offer uninsured/underinsured motorist (UM/UIM) coverage. This protection matters because not all drivers carry adequate insurance. Understanding when and how to use this coverage ensures you have a path to recovery even if the at-fault driver’s policy limits are exhausted.
Step 1: Report the Accident Immediately
Call 911 if anyone is injured or there is significant property damage; a police report creates an official record that insurers rely on. Exchange contact and insurance information with the other driver(s) at the scene, including names, phone numbers, addresses, insurance company names, and policy numbers.
Report the accident to your own insurance company as soon as possible. Most policies require prompt notice, and delays can give the insurer grounds to deny your claim. When you call, provide factual details only: the date, time, and location of the accident; the other driver’s information; and a brief description of what happened. Do not admit fault or speculate about what caused the accident. Statements like “I’m sorry” or “it was my fault” can be used against you later.
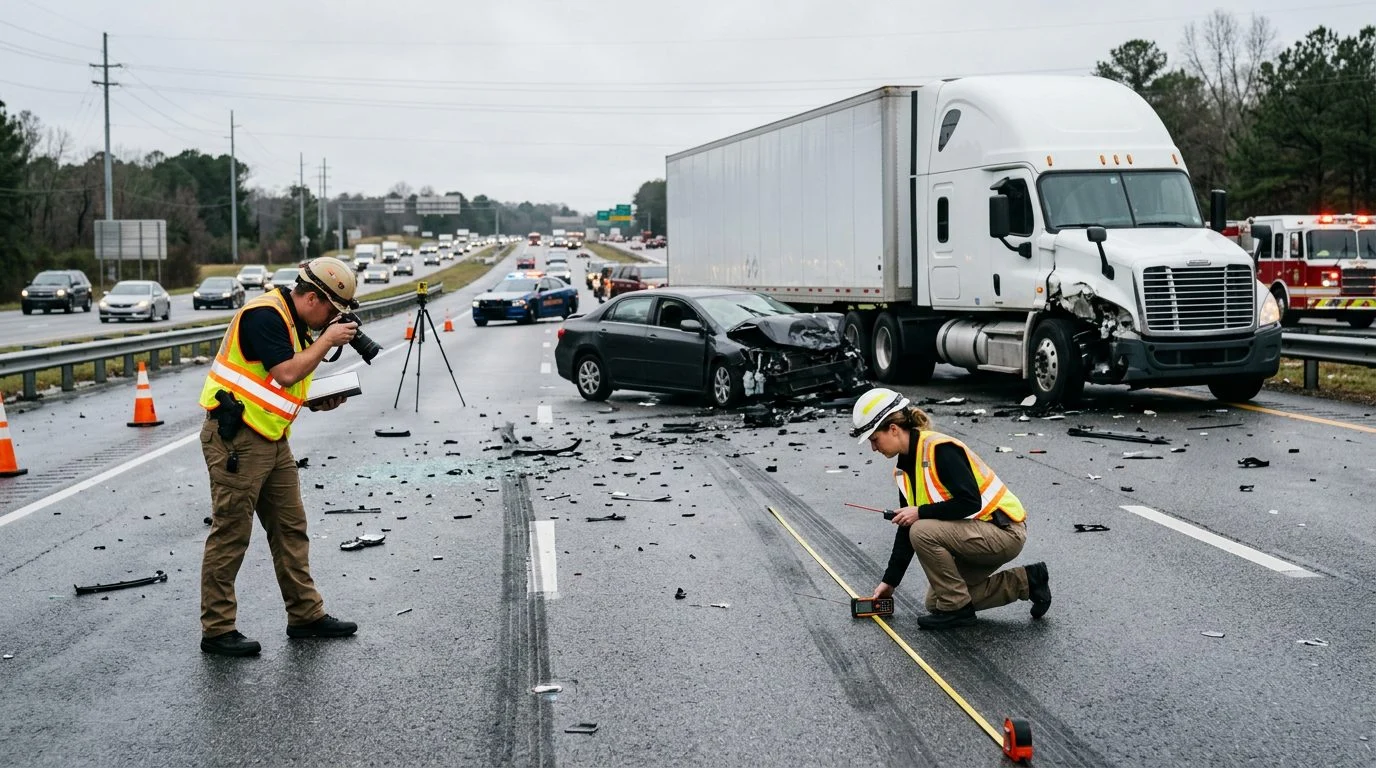
If it’s safe to do so, document the scene with photos or video. Capture vehicle damage, road conditions, traffic signs, weather, and the position of the vehicles. Take photos of any visible injuries. If there are witnesses, ask for their contact information and a brief account of what they saw. This evidence becomes critical if liability is later disputed.
Step 2: Gather Evidence and Documentation
Obtain the police report number at the scene and request a copy from the Georgia State Patrol or your local law enforcement agency. The police report is one of the most important documents in your claim; it contains the officer’s observations, statements from both drivers, witness information, and an initial assessment of fault.
Collect all medical records and bills related to injuries from the accident. This includes emergency room visits, hospital stays, doctor’s appointments, imaging (X-rays, MRI scans), physical therapy, and prescription medications. Keep receipts for all accident-related expenses: vehicle rental while yours is being repaired, medical co-pays, transportation to appointments, and any other out-of-pocket costs.
Document lost wages with recent pay stubs or a letter from your employer stating the dates you missed work and your hourly rate or salary. If you’re self-employed, provide tax returns or business records showing your typical income.
Preserve all photos, video, and witness contact information from the scene. Save every written communication with insurance companies and adjusters—emails, letters, text messages. These records protect you if there’s a dispute later about what was said or promised.
Step 3: File Your Claim with the At-Fault Driver’s Insurer (Third-Party Claim)
If the other driver is at fault, you can file a claim with their insurance company. This is called a “third-party claim” because you’re claiming against someone else’s policy, not your own.
Contact the at-fault driver’s insurance company and provide your contact information, vehicle details, the accident date and location, and the police report number. Submit supporting documentation: medical records, repair estimates, photos, witness statements, and any other evidence that supports your claim.
The insurer will assign an adjuster to investigate and evaluate your claim. Be honest and complete in your statements, but do not volunteer information beyond what is asked. You have the right to decline a recorded statement or to have an attorney present if the adjuster requests one.
Step 4: The Insurance Adjuster’s Investigation
The adjuster reviews the police report, your statement, the other driver’s statement, and physical evidence to determine liability and assess damages. The adjuster may request a recorded statement from you; you have the right to decline or to have an attorney present.
The adjuster may inspect the vehicle damage and obtain repair estimates from body shops. They may contact your medical providers to verify treatment and costs. They may also request authorization to obtain your medical records directly from healthcare providers.
The investigation typically takes 2–4 weeks, though complex cases—especially those involving serious injuries or disputed liability—may take longer. During this time, stay in contact with the adjuster and promptly provide any additional information they request.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Step 5: Liability Determination and Damage Assessment
Under this rule, if you’re found to be 30% at fault and the other driver is 70% at fault, you can still recover 70% of your damages.
The insurer will assign a percentage of fault to each party based on the evidence. This determination is crucial because it affects how much you can recover. If liability is unclear or disputed, the process may take longer as the insurer gathers additional evidence or consults with experts.
Damages include medical expenses, lost wages, vehicle repair or replacement, and pain and suffering (compensation for physical pain and emotional distress). The insurer will calculate a settlement offer based on the policy limits, the liability percentage, and your documented damages.
Step 6: Settlement Negotiation and Resolution
The insurer will make an initial settlement offer. This offer is often lower than the full value of your claim—it’s a starting point for negotiation, not a final number.
You have the right to negotiate and request additional compensation if the offer doesn’t cover your damages. Provide any new evidence or documentation that supports a higher settlement: additional medical records, updated wage loss calculations, or expert opinions about the extent of your injuries.
Settlement discussions may take weeks or months depending on the complexity of the case. Once you and the insurer agree on a settlement amount, you’ll sign a release form and receive payment. The release typically prevents you from pursuing further claims related to the accident, so understand what you’re giving up before you sign.
Filing a Claim with Your Own Insurer (First-Party Claim)
If the at-fault driver is uninsured or underinsured, you may file a claim with your own insurance company. This is called a “first-party claim” because you’re claiming against your own policy.
Georgia law requires insurers to offer uninsured/underinsured motorist (UM/UIM) coverage. Your own insurer will investigate and may offer a settlement for damages not covered by the at-fault driver’s policy. Your deductible applies to first-party claims; you pay this amount before the insurer covers the rest.
The process is similar to a third-party claim but typically moves faster since your own insurer has a financial incentive to resolve it. However, your insurer may be more aggressive in investigating your own conduct and injuries since they’re the ones paying.
Common Challenges and How to Avoid Them
Delaying the claim: Report the accident and file your claim promptly. Delays can result in lost evidence, faded memories, and missed deadlines. Some insurers may deny claims if notice is unreasonably delayed.
Accepting the first offer: Initial settlement offers are often below fair value. Negotiate before accepting. If you’re unsure whether an offer is fair, you can ask us to review it before you respond.
Admitting fault: Never say “I’m sorry” or “it was my fault” at the scene or in communications with the insurer. Let the investigation determine liability based on evidence, not your words.
Posting about the accident on social media: Insurers monitor social media. Anything you post—photos, comments about your injuries, statements about the accident—can be used against you to minimize your claim.
Failing to document expenses: Keep all receipts and records. Without documentation, insurers may deny reimbursement. A receipt for a medical co-pay or vehicle rental is proof; your word alone is not.
Signing a release too quickly: Understand what you’re giving up before you sign. A release is usually permanent and prevents you from pursuing any further claims related to the accident.
When to Seek Legal Guidance
If your injuries are serious or the medical bills are substantial, an attorney can help ensure you receive fair compensation. Serious injuries often have long-term consequences and costs that aren’t immediately obvious.
If liability is disputed or unclear, an attorney can gather evidence and negotiate on your behalf. Insurance companies have experienced adjusters and attorneys; having your own advocate levels the playing field.
If the insurer denies your claim or offers an unreasonably low settlement, an attorney can challenge the decision and pursue additional remedies.
If the at-fault driver is uninsured or underinsured and your damages exceed available coverage, an attorney can explore other options—such as claims against your own UM/UIM coverage or other potential defendants.
If you’re unsure about your rights or the claims process, a consultation can clarify your next steps and help you avoid costly mistakes.
If you've been injured in a truck accident and the insurance process feels overwhelming, we help people in your situation understand their options and protect their rights—reach out for a free case review. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
FAQ
Can I recover damages if I was partially responsible for the truck accident?
Yes, under Georgia’s modified comparative negligence rule, you can recover damages as long as you’re less than 50% at fault.
What if the truck driver is uninsured or underinsured?
You can file a claim with your own insurance company under your uninsured/underinsured motorist (UM/UIM) coverage, subject to your policy limits and deductible.
Should I give a recorded statement to the insurance adjuster?
You have the right to decline or to have an attorney present. Be cautious; recorded statements can be used against you if the insurer later disputes your injuries or the accident’s cause.
What documents do I need for a truck accident insurance claim?
Collect the police report, medical records and bills, repair estimates, photos from the scene, witness contact information, pay stubs or wage-loss documentation, and receipts for all accident-related expenses.
If you’ve been injured in a truck accident and the insurance process feels overwhelming, we help people in your situation understand their options and protect their rights. Reach out for a free case review to talk through your situation and your options.
The Truck Accident Claim Process: Step by Step
Step 1: Document the Scene & Report the Accident
Gather photos, witness contact information, and the truck driver's insurance details at the scene. Report the accident to the police and file a report with your own insurance company promptly. These records form the foundation of your claim.
Step 2: Seek Medical Attention & Keep Records
Get evaluated by a doctor even if injuries seem minor—some develop over time. Keep all medical bills, treatment notes, and receipts. These documents prove the extent of your damages and support your claim value.
Step 3: Notify the Truck Driver's Insurance
Provide the insurer with your claim details, medical records, and repair estimates. Be factual and avoid admitting fault or overstating injuries. Stick to documented facts.
Step 4: Negotiate & Pursue Fair Resolution
The insurer will make an offer. If it doesn't reflect your actual losses, you can counter and negotiate. Many claims settle without court; others require further action to reach a fair outcome.
Important: Comparative Negligence in Georgia
Under Georgia’s modified comparative negligence rule, you can recover damages only if you were less than 50% at fault for the accident; if you are 50% or more at fault, you recover nothing. However, your recovery is reduced by your percentage of fault. Understanding how fault is assigned is critical to your claim.
Why Professional Guidance Matters
Protect Your Rights
Before you accept any settlement offer, you may want to speak with a lawyer about your options under Georgia law.
Build a Strong Claim
Proper documentation, medical evidence, and damage assessment are essential. We help gather and organize the records that support your claim.
Handle Delays & Disputes
When insurers drag out negotiations or deny claims, we can discuss negotiation or litigation options with you.
Clear Communication
We explain the process in plain language, answer your questions, and keep you informed every step of the way.
You may still be responsible for certain case costs such as court filing fees, investigation expenses, and expert witness fees, which we can discuss with you upfront.
Ready to Move Forward?
Related practice areas
- Truck Accident Lawyers in Duluth & Metro Atlanta, GA
- Georgia Truck Accident Statute of Limitations: 2-Year