
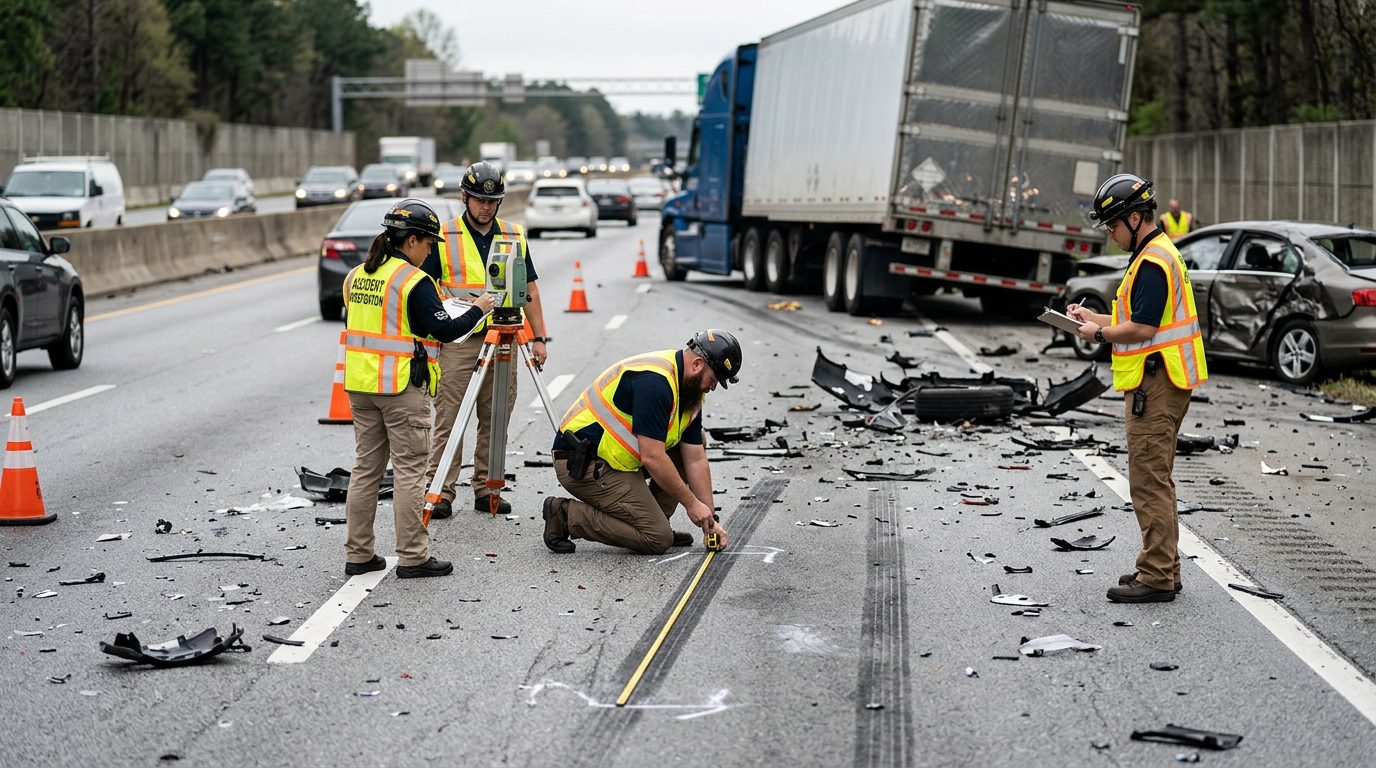
Truck Accidents in Georgia
Protect Your Assets After a Truck Accident
A serious truck collision can threaten your financial security. Learn what you need to know about liability, insurance, and your rights.
By Peter F. Jaraysi · Published September 28, 2026
How to Protect Your Assets After a Truck Accident in Georgia
If you’ve been in a truck accident in Georgia, you may be facing more than just physical injuries and vehicle damage. Depending on who caused the accident and the severity of injuries, you could face significant financial liability—and your personal assets may be at risk if the damages exceed your insurance coverage.
Understanding how liability works, what assets a judgment creditor can pursue, and how to use insurance and proper claim handling to shield yourself is essential. This guide walks you through the real financial exposure you face and the concrete steps to protect yourself.
If you've been in a truck accident and worry about your financial exposure or whether your personal assets could be at risk, reach out—people in your situation contact us regularly to understand their options. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Understanding Your Financial Exposure After a Truck Accident
When someone is injured in a truck accident, the at-fault party is legally responsible for covering the injured person’s damages—medical bills, lost wages, pain and suffering, and property damage. That responsibility doesn’t disappear just because insurance is involved.
Georgia’s minimum auto insurance requirement is $25,000 for bodily injury per person and $50,000 per accident. But serious truck accidents routinely result in damages far exceeding these limits. A single hospitalization, surgery, and ongoing care can easily surpass $100,000. When damages exceed your coverage, you become personally liable for the difference.
The gap between minimum coverage and actual damages is where your personal assets enter the picture. If you’re found at fault and a judgment is entered against you for $200,000, but your insurance only covers $50,000, you owe the remaining $150,000 from your own pocket.
Georgia follows a comparative fault rule, meaning if you’re found partially at fault for the accident, your liability is reduced by your percentage of fault. But that protection only goes so far—significant damages can still exceed your coverage.
Which of Your Assets Can Be at Risk
Under Georgia law, a judgment creditor (the person who won the judgment against you) can pursue collection against multiple types of your assets:
Bank accounts and savings. Judgment creditors can freeze and seize funds in checking, savings, and investment accounts once they obtain a judgment and identify where you bank.
Real estate and home equity. Your home is not fully protected. Georgia provides a homestead exemption that shields up to $25,000 of home equity from judgment creditors for most homeowners. If your home is worth $300,000 and you owe $100,000 on the mortgage, you have $200,000 in equity—and $175,000 of that is vulnerable to judgment collection.
Wages and future income. Judgment creditors can garnish your wages. Georgia law allows garnishment of up to 25% of your disposable income to satisfy a judgment. That means a portion of every paycheck can be diverted until the judgment is paid.
Vehicles and titled property. Cars, trucks, boats, and other titled property can be seized to satisfy a judgment, though one vehicle may be protected depending on its value and your circumstances.
What is protected. Your primary residence homestead exemption ($25,000), certain retirement accounts (like IRAs and 401(k)s under federal law), and essential personal property have some protection. But these exemptions are limited and don’t shield all your assets.
Insurance Coverage: Your First Line of Defense
The best protection against personal asset exposure is adequate insurance coverage. Most people don’t realize how thin their coverage actually is until after an accident.
Liability limits on your auto policy. If your policy has the state minimum ($25,000/$50,000), you’re underprotected. Serious truck accidents involving multiple injuries or permanent disability can generate damages in the hundreds of thousands. Increasing your liability limits to $100,000/$300,000 or higher is one of the most cost-effective ways to reduce your personal exposure.
Underinsured motorist (UIM) coverage. This coverage protects you when the at-fault party’s liability insurance is insufficient. If the truck driver is at fault but their insurance only covers $50,000 and your damages are $150,000, your UIM coverage bridges the gap—up to your UIM limit. Georgia law allows stacking of UIM coverage across multiple vehicles in certain circumstances, which can significantly increase your protection.
Uninsured motorist (UM) coverage. If the truck driver is uninsured, UM coverage covers your damages up to your policy limit. This is essential protection in Georgia, where uninsured drivers are common.
Medical payments (Med Pay) coverage. This covers your own medical expenses regardless of fault and doesn’t count against your liability limits. It’s a valuable first-line protection that covers treatment costs immediately.
Reviewing your current policy limits now—before an accident—is one of the smartest financial decisions you can make.
Additional Protection Strategies
For higher-net-worth individuals or those with significant assets, additional layers of protection exist:
Umbrella or excess liability insurance. Umbrella policies typically provide $1 million or more in additional coverage beyond your auto policy limits. They’re one of the most effective asset protection tools available and are surprisingly affordable—often $150 to $300 per year for $1 million in coverage. Umbrella policies activate only after your underlying auto policy limits are exhausted, making them a cost-effective safety net.
Homeowners or renters insurance. These policies sometimes include additional liability protection that can supplement your auto coverage in certain situations.
Business liability insurance. If you own a business, a separate business liability policy may provide additional protection.
The key principle: adequate coverage before an accident occurs is far more effective—and less expensive—than trying to protect assets after a judgment is entered.
How Proper Claim Handling Protects Your Assets
Beyond insurance, how you handle a claim after the accident directly affects your financial exposure. Poor decisions early on can undermine your position and increase your liability.
Early documentation matters. Photographs of the accident scene, vehicle damage, road conditions, and traffic signals; witness statements; the police report; and medical records all support your account of what happened. This evidence strengthens your negotiating position and can help establish that the other driver was at fault—or that you bore less responsibility than claimed.
Avoid admissions of fault. Statements to the other driver’s insurance company admitting fault or minimizing injuries can be used against you in settlement negotiations. Insurance adjusters are trained to extract statements that increase your liability. Without legal guidance, it’s easy to say something that damages your position.
Professional representation improves settlements. An attorney handles negotiations with insurance companies, ensures your damages are fully documented, and works to settle claims within available coverage limits. Settling within your insurance coverage—rather than allowing a judgment to exceed it—is one of the most effective ways to protect your personal assets.
Preserve all records. Keep detailed records of all accident-related expenses, medical treatment, lost wages, and communications with insurance companies. These documents support your damage claim and help ensure fair compensation.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Steps to Take Immediately After a Truck Accident
Report the accident promptly. Contact your insurance company as soon as possible. Delays can complicate coverage or give the other party an advantage.
Gather evidence at the scene. Take photos of vehicle damage, the accident scene, road conditions, traffic signals, and street signs. Get names and contact information from witnesses and the police officer who responds.
Seek medical attention. Even if you feel fine, some injuries emerge days or weeks later. Medical records documenting your injuries are essential to your claim.
Document all expenses. Keep receipts for medical treatment, vehicle repairs, rental cars, and other accident-related costs.
Avoid statements to the other driver’s insurance. Don’t discuss the accident or your injuries with the other driver’s insurance company without legal guidance. Stick to factual statements and avoid speculation about fault.
Review your coverage. After the accident, review your policy limits and coverage options. This helps you understand your protection and identify gaps.
When to Seek Legal Guidance
You should consider legal representation if:
- Your injuries are serious or property damage is significant, increasing the risk that damages will exceed your coverage.
- Multiple people were injured, creating complex liability questions.
- You’re in dispute with your own insurance company over coverage or settlement.
- You’re concerned about personal asset exposure or the risk of a judgment exceeding your insurance.
In the truck accident cases our attorneys handle, we’ve seen how early professional guidance—before statements are made or settlement offers are accepted—often makes the difference between a manageable resolution and years of wage garnishment or asset collection.
Frequently Asked Questions
What’s the difference between liability limits and underinsured motorist coverage?
Liability limits cover damages you cause to others; underinsured motorist coverage covers your damages when the at-fault party’s insurance is insufficient.
Can my home be taken to pay a truck accident judgment in Georgia?
Your home has some protection under Georgia’s homestead exemption, but only up to $25,000 of equity. Equity beyond that amount can be subject to judgment collection.
How much umbrella insurance do I need?
For most people, $1 million in umbrella coverage is a good starting point. Higher-net-worth individuals may want $2 million or more. An insurance agent can help you assess your specific situation.
What happens if I ignore a judgment?
Judgment creditors can pursue wage garnishment, freeze bank accounts, and place liens on property. The longer a judgment sits unpaid, the more aggressive collection efforts become.
Can my wages really be garnished in Georgia?
Yes. Judgment creditors can garnish up to 25% of your disposable income, with some exceptions for child support and other priority debts.
If you’ve been in a truck accident and worry about your financial exposure or whether your personal assets could be at risk, reach out—people in your situation contact us regularly to understand their options. Request a free consultation to discuss your accident, your coverage, and how we can help protect your financial future.
For more information on truck accident liability and your rights, see our guide on truck accidents.
Important: Georgia Homestead Protection
Georgia law provides some protection for your primary residence in certain judgment situations. The specifics depend on your circumstances, the judgment amount, and when the judgment was entered. Understanding what protections may apply to you requires a careful review of your case.
Key Questions About Asset Protection After a Truck Accident
What's the difference between liability limits and underinsured motorist coverage?
Liability limits cover damages you cause to others; underinsured motorist coverage protects you when the at-fault party's insurance is insufficient to cover your losses.
How does Georgia law treat judgment liens?
A judgment creditor may place a lien on your property to secure payment. Certain assets have statutory protections, but the rules are complex and depend on your specific situation.
What role does insurance play in protecting my assets?
Adequate liability and uninsured/underinsured motorist coverage can shield your personal assets from direct liability. An attorney can help you understand your current coverage and any gaps.
Should I be concerned about a judgment affecting my future income?
Georgia law limits wage garnishment in certain cases, but a judgment can still create serious financial consequences. Early legal guidance helps protect your interests.
How Slam Dunk Attorney Can Help
Understand Your Coverage
We review your insurance policies to identify what protections are in place and what gaps may exist after a truck accident.
Navigate Complex Claims
Insurance negotiations and liability disputes can be complicated. We handle the process so you can focus on recovery.
Protect Your Rights
We explain your options clearly and work to preserve your financial security throughout the claims and legal process.
Available When You Need Us
A serious truck accident creates urgent questions. We're here to answer them and guide you through next steps.