
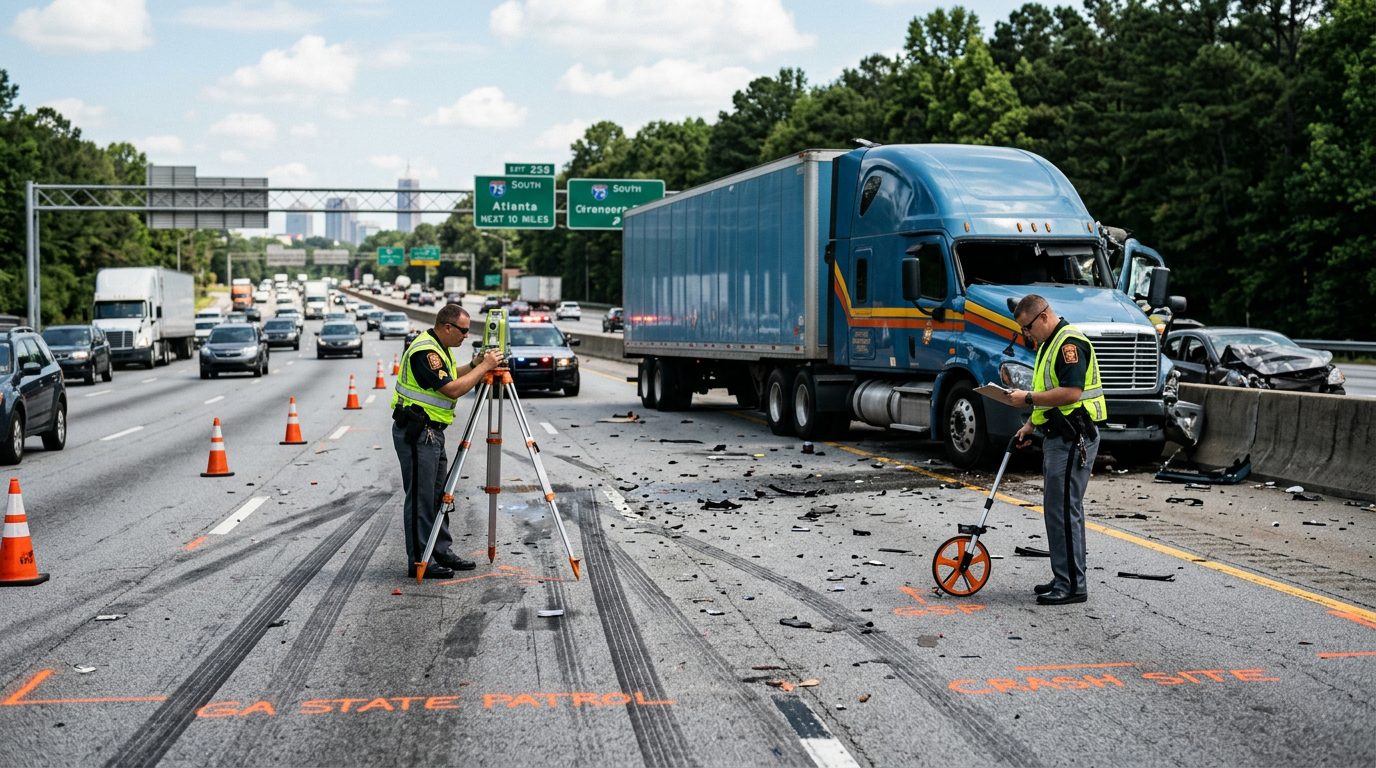
Truck Accident | Georgia
Medical Bills After a Truck Accident in Georgia
Understanding your coverage options and how to recover costs from the at-fault driver.
By Peter F. Jaraysi · Published October 04, 2026
Medical Bills After a Truck Accident in Georgia: Who Pays and How
After a truck accident, medical bills can pile up fast—emergency room visits, imaging, surgery, physical therapy. The good news is that multiple sources may help cover these costs in Georgia. Understanding how each one works helps you know what to expect and what options are available to you.
If you're navigating medical bills after a truck accident and aren't sure which insurance covers what, we can walk you through your options—many people in your situation reach out to talk through next steps. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Overview: Multiple Sources May Cover Your Medical Bills
In Georgia, medical bills after a truck accident can be paid from several sources depending on your insurance coverage and who caused the accident. The at-fault driver’s liability insurance is typically the primary source, but it’s often not the only one. You may also have coverage through your own auto insurance policy, your health insurance, or specialized motorist coverage. Knowing which source applies when helps you manage bills while your claim moves forward.
The At-Fault Driver’s Liability Insurance
Georgia is an at-fault state: the driver responsible for the accident is liable for damages, including medical bills. The at-fault driver’s liability insurance should cover your reasonable and necessary medical expenses caused by the crash.
Here’s how it works in practice. After the accident, you file a claim with the at-fault driver’s insurance company. They investigate the accident, review police reports, and determine whether their driver was responsible. If they accept liability, they should pay your medical bills up to the policy’s liability limit. If they dispute liability or delay, the process takes longer.
One important catch: liability coverage has limits. In Georgia, the minimum liability coverage is $25,000 for bodily injury per person. If your medical bills exceed that limit—which happens in serious truck accidents—the at-fault driver’s insurance may not cover everything. That’s where your own coverage comes in.
Your Own Medical Payments Coverage (MedPay)
Medical Payments (MedPay) coverage is optional coverage you can add to your own auto insurance policy. It covers medical expenses for you and your passengers regardless of who caused the accident.
MedPay is “first-party” coverage, meaning you claim it from your own insurer, not the other driver’s. It typically covers bills up to your chosen limit—often $1,000 to $5,000 or more, depending on what you selected when you bought the policy. MedPay pays quickly and doesn’t require waiting for a liability determination. You can use it to cover copays, deductibles, ambulance fees, hospital stays, and follow-up care.
If you have MedPay, check your policy declarations page to see your limit. Many people don’t realize they have this coverage until they need it.
Personal Injury Protection (PIP) Coverage
Georgia does not require Personal Injury Protection (PIP), but some insurance policies include it. PIP covers medical expenses, lost wages, and other accident-related costs for you and your passengers, regardless of fault.
Like MedPay, PIP is first-party coverage and pays quickly. The main difference is scope: PIP typically covers more than just medical bills—it may also cover lost income, childcare, and household services while you recover. PIP limits and coverage details vary by policy, so check your declarations page to see if you have it and what your limit is.
Your Health Insurance
Your health insurance may cover medical treatment after a truck accident. You typically pay your regular copay or deductible, and your health plan covers the rest of the bill.
Here’s what matters for your claim: your health insurance company may place a lien on your settlement to recover what they paid. This is called a “medical lien” or “subrogation.” The health plan is saying, “We paid for your treatment; we want repaid from your recovery.” Medical liens are common in Georgia truck accident cases and can reduce the amount you take home from a settlement.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Medical Liens and How They Work
A medical lien is a claim by a healthcare provider or health insurance company against your settlement or judgment. The provider or insurer paid for your treatment and wants to be repaid from the money you recover.
Here’s the process. You settle your case for, say, $50,000. Your health insurance paid $15,000 in medical bills during your treatment. They place a lien for $15,000. When the settlement closes, that $15,000 is paid directly to the health insurance company from your recovery before you receive your portion. You get the remainder.
The good news: many medical liens are negotiable. Healthcare providers and insurance companies may accept less than the full amount owed, especially if you explain your situation or if a lawyer negotiates on your behalf. Some providers will reduce a lien by 25–50% to help you.
Keep all medical bills and explanations of benefits (EOBs) from your health insurance. These documents show exactly what was paid and help you verify lien amounts later.
What Happens If the At-Fault Driver Is Uninsured or Underinsured
If the at-fault truck driver has no insurance or insufficient coverage, your medical bills may not be fully covered by their liability policy. This is where your own Uninsured/Underinsured Motorist (UM/UIM) coverage helps.
UM/UIM coverage is optional in Georgia but strongly recommended. It covers your medical bills and other damages when the at-fault driver has no insurance or their coverage is too low. Without UM/UIM, you may have to rely on your health insurance, MedPay, or PIP alone—and those sources have limits.
Check your auto insurance policy to see if you have UM/UIM coverage and what your limit is.
How Much of a Settlement Goes to Medical Bills?
Medical bills are part of your “damages”—the total harm the accident caused you. Your settlement or judgment should cover all reasonable medical expenses caused by the crash.
However, the amount you actually take home depends on several factors. Liens, insurance subrogation, and other claims reduce the amount you receive. For example, if your settlement is $50,000 and medical liens total $15,000, you take home $35,000 before attorney fees and court costs (if any). The exact breakdown depends on your specific injuries, treatment costs, insurance coverage, and the settlement amount.
Managing Medical Bills While Your Claim Is Pending
Medical bills often arrive quickly, sometimes before your claim is resolved. Don’t let them go unpaid or to collections—this damages your credit and complicates your case.
Contact your healthcare providers and ask about payment plans or hardship programs. Let them know a claim is pending; many providers will work with you or hold bills while you resolve the claim. Some hospitals have financial assistance programs for uninsured or underinsured patients.
Keep detailed records of all medical expenses and bills. Take photos of invoices, save emails, and organize EOBs from your health insurance. These documents are essential for your claim.
What Not to Tell the Insurance Company
When you speak with the at-fault driver’s insurance company, be careful about what you say:
- Don’t admit fault. Even a casual “I’m sorry” can be interpreted as an admission of liability.
- Don’t exaggerate or downplay your injuries. Stick to the facts. Inconsistencies hurt your credibility.
- Don’t discuss your case on social media or with others. What you share can be used against you.
- Don’t accept a settlement offer without understanding all your medical bills and future treatment needs. Once you settle, you can’t ask for more money later.
- Don’t sign documents or give recorded statements without understanding what you’re agreeing to. If you’re unsure, ask questions or talk to a lawyer first.
If you're navigating medical bills after a truck accident and aren't sure which insurance covers what, we can walk you through your options—many people in your situation reach out to talk through next steps. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
How Long Does an Insurance Company Have to Settle in Georgia?
Georgia law requires insurance companies to acknowledge your claim promptly and investigate in good faith. There is no fixed deadline for settlement, but unreasonable delays can be grounds for a bad-faith claim.
Simple claims may settle in weeks. Complex cases with serious injuries, multiple treatment providers, or disputed liability can take months or longer. If the insurance company is stalling, refusing to communicate, or offering far less than your bills and injuries warrant, you may need to file a lawsuit. Georgia’s statute of limitations for personal injury claims is two years, so you have time—but don’t wait too long.
Frequently Asked Questions
What is the difference between MedPay and PIP?
MedPay covers only medical expenses; PIP typically covers medical bills, lost wages, and other accident-related costs. Both pay regardless of fault and pay quickly.
Can I use both my health insurance and MedPay?
Yes. Your health insurance is primary; MedPay can cover copays, deductibles, and costs your health plan doesn’t cover.
Are medical liens always enforceable?
Medical liens are generally enforceable, but the amount is often negotiable. Many providers will accept less than the full amount owed.
What if I don’t have health insurance or MedPay?
Your PIP coverage (if you have it) or the at-fault driver’s liability insurance should cover your bills. If the at-fault driver is uninsured, your UM/UIM coverage helps.
Can I negotiate with healthcare providers about bills?
Yes. Contact providers directly and explain your situation. Many will work with you on payment plans or reduce bills, especially if you’re waiting for a settlement.
What Comes Next
If you’re facing large medical bills after a truck accident and aren’t sure which insurance source applies to your situation, or if an insurance company is moving slowly, talking through your options can help clarify what’s available to you. Many people in your position reach out to discuss next steps before they’ve decided what to do—that conversation is free and confidential. Contact us to talk about your situation.
Coverage That May Pay Your Medical Bills
Medical Payments (MedPay)
Part of your auto insurance policy. Covers medical expenses regardless of fault and pays quickly. Limits vary by policy, typically $1,000–$5,000.
Personal Injury Protection (PIP)
Available in some Georgia policies. Covers medical bills, lost wages, and related costs without regard to fault. Pays faster than waiting for a liability claim.
At-Fault Driver's Liability Insurance
The truck driver's insurance may cover your medical bills if they are found liable. This process takes longer but can cover higher amounts.
Your Health Insurance
Your primary coverage. Copays and deductibles may apply. MedPay or PIP can often cover these out-of-pocket costs.
Important: Preserve Your Right to Recovery
Medical providers and insurers may place a lien on your settlement to recover what they paid for your care. Accepting a settlement without understanding these obligations can reduce what you actually receive. Understanding your bills and liens early protects your recovery.
How Slam Dunk Attorney Helps with Medical Bills
Organize and Review Your Bills
We collect and review all medical records and bills to ensure accuracy and identify any overcharges or duplicate billing.
Identify All Available Coverage
We determine which insurance policies—yours, the at-fault driver's, and others—may cover your care and in what order.
Manage Liens and Negotiation
We communicate with medical providers and insurers about liens and work to reduce them when possible, protecting more of your recovery.
Explain Your Options Clearly
We explain what you owe, what coverage applies, and what settlement offers mean for your actual take-home amount—in plain language.
Common Questions About Medical Bills After a Truck Accident
What if my medical bills exceed my insurance coverage?
You may pursue a claim against the at-fault truck driver's liability insurance or their employer. A personal injury claim can seek compensation for bills, lost wages, pain, and other damages.
Can I use both my health insurance and MedPay?
Yes. Health insurance is typically primary; MedPay can cover copays, deductibles, and costs your health plan doesn't cover. Coordinate benefits to maximize coverage.
Who pays if the truck driver was uninsured or underinsured?
Your own uninsured or underinsured motorist (UIM) coverage may apply. We help you file and pursue these claims to cover unpaid medical bills.
How long do I have to file a claim for medical bills?
Insurance claims and personal injury lawsuits have different deadlines. We review your situation and ensure all claims are filed on time.
Don't Settle Without Understanding Your Bills
Many accident victims accept settlements without realizing how much will go to medical providers, insurers, and liens. The result: far less money in your pocket than you expected. We make sure you understand every dollar before you agree to anything.
Let's Review Your Medical Bills and Recovery Options
Related practice areas
- Truck Accident Lawyers in Duluth & Metro Atlanta, GA
- Recorded Statements After Truck Accidents in Georgia