
Catastrophic Injuries | Duluth, Georgia
Planning Ahead After a Catastrophic Injury in Georgia
A life care plan lays out the medical treatment, therapy, equipment and daily support a serious injury may require for years to come. Here is how it works and how our team can help you prepare.
By Peter F. Jaraysi · Published October 27, 2026
A life care plan for a catastrophic injury is a written estimate of the medical, therapy, equipment, and daily-living care a seriously injured person will likely need for the rest of their life. It turns an uncertain future into a list of specific needs and costs. This guide explains how these plans are built, how they fit into a Georgia injury claim, and what families in Duluth, Lawrenceville, Marietta, and across metro Atlanta can gather now.
What Is a Life Care Plan?
A life care plan is a document that projects the future care a person with a serious injury will likely need. It lists each need, explains why it’s needed, and estimates what it costs over time. Injuries such as paralysis, traumatic brain injury, amputation, and severe burns often create needs that last for decades. MedlinePlus paralysis overview describes paralysis as a loss of muscle function that can result from catastrophic injuries, such as spinal cord injuries or a broken neck.
Each item in a plan should tie back to something in the record. A surgeon’s recommendation, a therapist’s notes, or a doctor’s statement about equipment can anchor a line item. Without that link, a future need is only a guess. With it, the need has a basis.
Planners usually prepare the plan after the injured person’s condition has settled enough to project long-term needs. Early in treatment, doctors are often still deciding what care will be required. That is why a plan often comes months after the first hospital bills.
For the bigger picture on these injuries and the claims they support, read our guide on catastrophic injuries in Georgia.
Who Prepares a Life Care Plan and Why It Matters in a Claim
A life care planner is the professional who builds the plan. Many planners come from nursing, rehabilitation, or related health backgrounds. The planner reviews medical records, talks with the injured person and family, and consults with treating physicians about what care is needed.
Why does this matter in a claim? O.C.G.A. § 51-12-2 says general damages are those the law presumes to flow from any wrongful act. They can be recovered without proof of any amount. Special damages actually flow from the wrong, so they must be proved.
A life care plan usually shows the future costs an injury may create. Those costs are separate from bills already paid. Keeping that line clear helps a judge, jury, or insurer read the claim the same way. A plan built on thin records is also easier to challenge, so the sources behind each entry matter.
Common Elements of a Life Care Plan
Most plans group future needs into clear categories. Each category usually states what is needed, how often, and for how long. Typical items include:
- Medical visits and procedures: physician visits, emergency and hospital care, surgeries, diagnostic testing, and follow-up scans.
- Medications: prescriptions, pain management, and supplies needed for daily treatment.
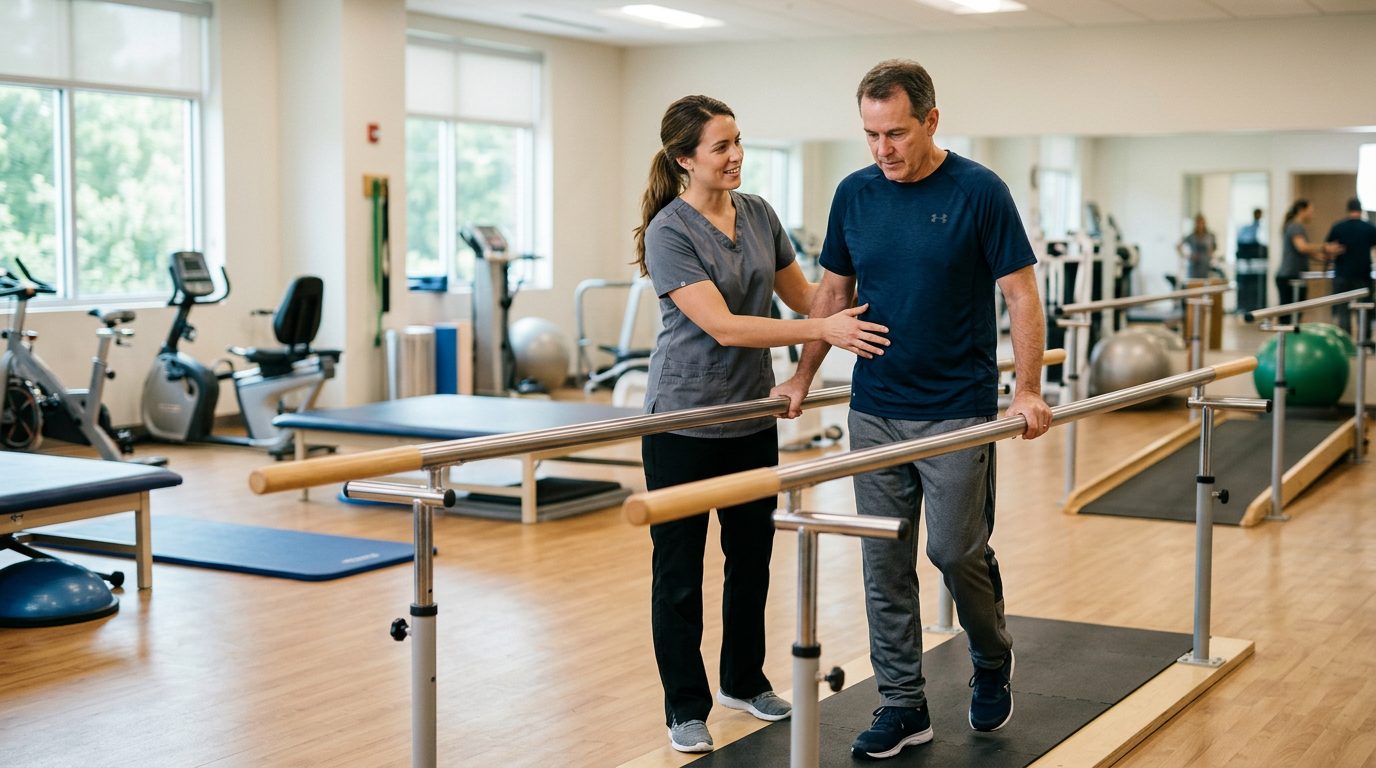
- Therapy: physical, occupational, speech, and cognitive therapy, with expected frequency and length.
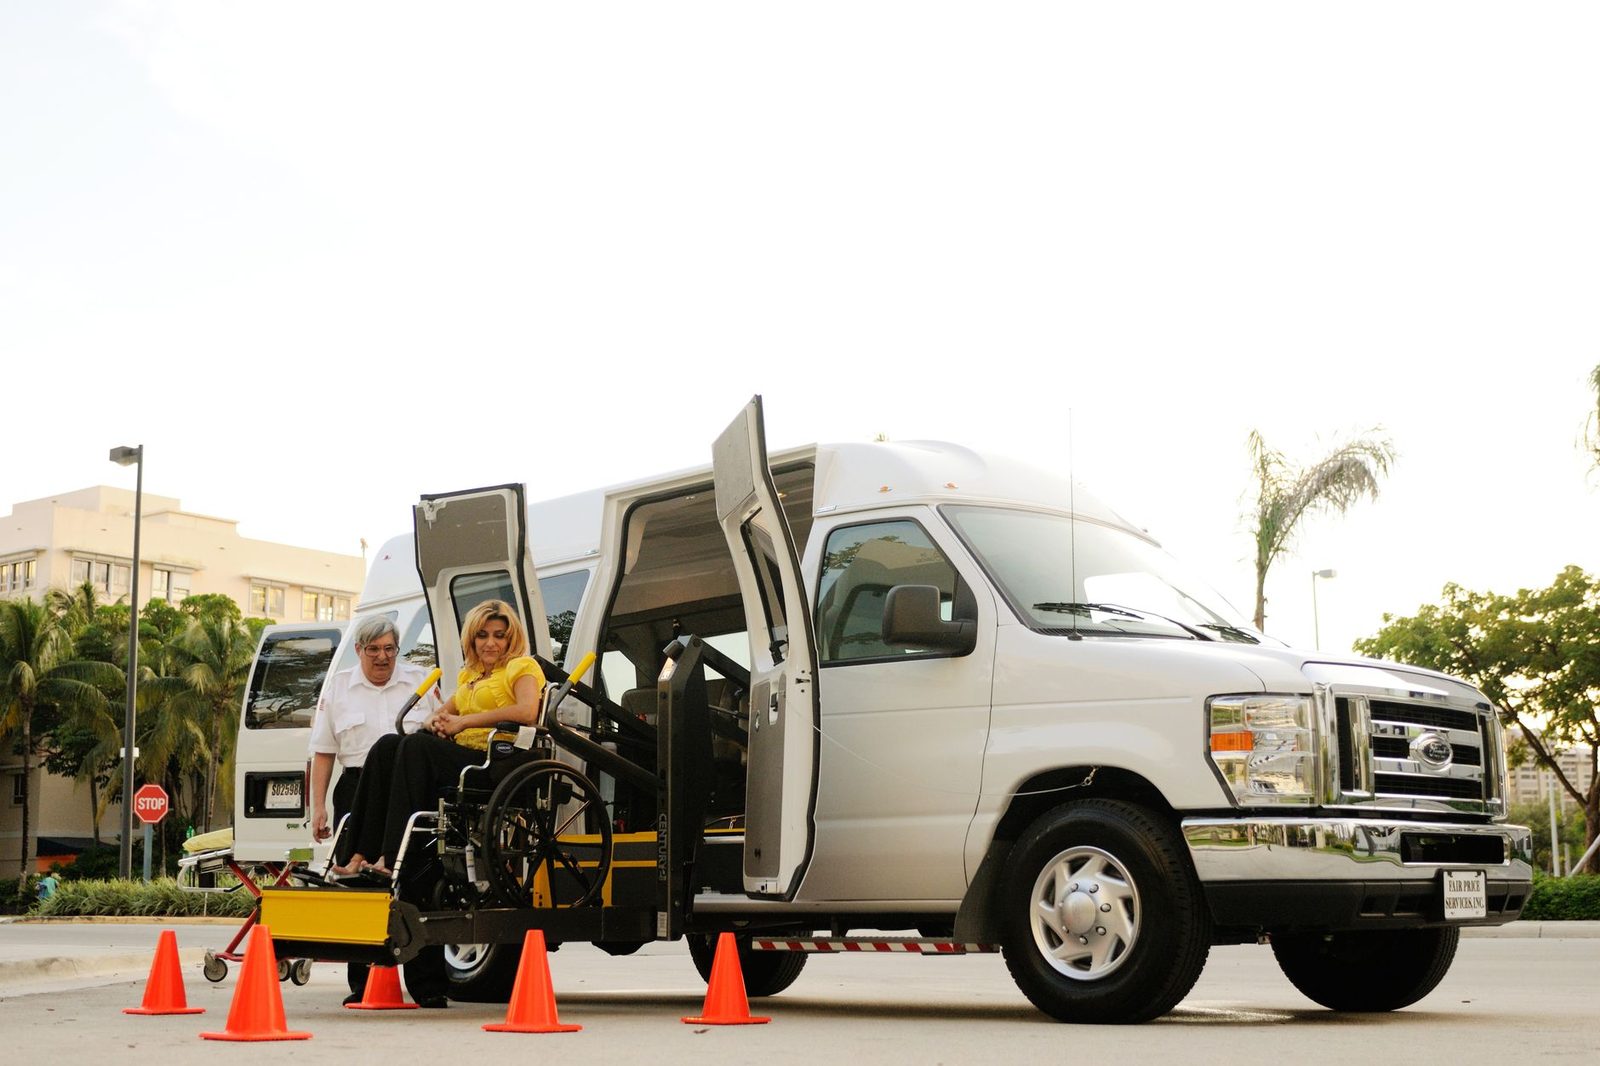
- Equipment and supplies: wheelchairs, braces, prosthetics and their replacement cycles, catheters, wound care supplies, and communication devices.
- Support care: attendant or home care, transportation to appointments, and help with housekeeping when the injury limits daily function.
- Home changes: accessibility work such as ramps, wider doorways, or bathroom modifications.
Each line often pairs a unit cost with a count. A plan might price a therapy session and then multiply it by the number of sessions expected each year. The math is only as good as its inputs.
Families often overlook supervision and caregiving time. When memory, judgment, or mobility is affected, someone may need to stay nearby. That time has a real cost, and a well-built plan shows it.
Care Needs for Spinal Cord, Brain, Amputation, and Burn Injuries
The type and location of an injury shape what a plan includes. Spinal cord injuries are often described by level (cervical, thoracic, lumbar, or sacral) and by whether the injury is complete or incomplete. Those details help decide the care that follows. spinal cord injury recovery research examines prognosis and recovery timelines after traumatic spinal cord injury.
After paralysis, long-term needs often include breathing and bladder care, pressure injury prevention, mobility equipment, and ongoing rehabilitation. Each one can continue for many years.
Brain injuries bring a different set of needs. The Brain Trauma Foundation prehospital guidelines state that traumatic brain injuries can range from mild to catastrophic. They may cause coma, death, serious morbidity, and substantial medical use. Lifetime needs can include neurological follow-up, cognitive and behavioral therapy, medication management, and supervision when judgment or memory is affected.
Amputation needs center on prosthetic fittings, refitting as the body changes, and gait training. Severe burns bring scar management, reconstructive procedures, and ongoing wound care. A good plan names each of these needs rather than grouping them under a general label.
How Future Costs Are Projected
Planners price each item using current cost data, provider rates, and estimates of how long care will be needed. The injured person’s age and life expectancy estimates shape how many years get counted. Every number in the plan is an estimate, and the estimate can change.
O.C.G.A. § 51-12-1.1 limits special damages for medical and healthcare expenses to the reasonable value of medically necessary care, treatment, or services. The trier of fact decides that amount. The same section allows evidence challenging the reasonableness of expenses, whether already incurred or projected, and the medical necessity of treatment.
Future dollars also get adjusted. O.C.G.A. § 51-12-13 says the trier of fact may reduce future medical expenses, living expenses, lost wages, and other economic damages to present value. It may use a 5 percent discount rate or any other rate it deems appropriate. In plain terms, money needed years from now may be valued lower today.
Costs also change as a person’s condition changes. A plan may need updates over time. For how these projected costs get funded, read our guide on who pays for lifetime care after a catastrophic injury.
How a Life Care Plan Fits Into a Georgia Injury Claim
A life care plan supports the claim for future medical costs and other future losses. Under O.C.G.A. § 51-12-7, necessary expenses that follow from an injury are a legitimate part of the damages estimate. The plan shows which future expenses are necessary and why.
The other side may push back. An insurer or defendant can hire its own reviewer. That reviewer may question the plan’s assumptions about needs, frequency, or cost. Common questions include how often therapy is really needed and whether a home change is required.
Fault matters, too. O.C.G.A. § 51-12-33 reduces damages by the plaintiff’s share of fault. A plaintiff found 50 percent or more responsible recovers nothing. Under O.C.G.A. § 51-12-33, when a plaintiff is to some degree responsible for the injury or damages claimed, the judge reduces the damages otherwise awarded in proportion to the plaintiff’s percentage of fault, and a plaintiff who is 50 percent or more responsible is not entitled to receive any damages.
Judges and juries usually read a plan alongside medical records, treating physician opinions, and other losses. Lost earning capacity is one of them. See our guide on lost earning capacity after a catastrophic injury in Georgia.
Liens, Health Insurance, and Government Programs
Health insurance and government programs can change how medical costs are proved and repaid. Many injured people have private coverage, Medicare, Medicaid, or workers’ compensation. Those payers may seek repayment from a settlement or judgment, depending on the facts.
Georgia’s medical-expense rule reaches insurance, too. O.C.G.A. § 51-12-1.1 says that if a plaintiff has any public or private health insurance, the evidence includes both the amounts charged and the amounts actually necessary to satisfy those charges. That holds whether or not the insurance has been used.
The same section covers care given under a letter of protection. That is an arrangement where a provider treats a patient in exchange for a promise of payment from a future judgment or settlement. The letter, itemized and coded charges, any sale of the provider’s receivables below invoice price, and the identity of any referrer are all relevant and discoverable.
A life care plan helps show how lifetime care costs relate to these payments and repayment claims. For more detail, see our guide on Medicare and Medicaid liens in catastrophic injury cases.
Documents to Gather Now
Start collecting records early. A few simple habits make a plan easier to build and easier to explain.
- Keep every medical record in one place. Include discharge summaries, imaging reports, and physician recommendations, in paper or digital form.
- Save receipts. Keep them for medications, equipment, medical supplies, and out-of-pocket care.
- Track mileage and help. Log trips to appointments and any rides or hands-on help a family member provides.
- Keep a daily log. Write down symptoms, limits, and the help needed for bathing, dressing, cooking, and other everyday tasks. Date each entry.
- List every provider. Record names, phone numbers, and visit dates for each treating provider.
A daily log matters because it captures limits in the person’s own words, with dates attached. A short office visit can miss these details, but a planner and a physician can use them.
Talk Through Your Situation With Our Team
A life care plan is a tool for the future. Questions about lifelong care often come before any plan exists. If a crash, a rideshare trip, a fall, or a dog attack left you or a family member with a spinal cord injury, brain injury, amputation, or severe burns, those questions can feel urgent.
How long do I have to file a lawsuit in Georgia?
Georgia’s general deadline for a personal-injury lawsuit is two years after the right of action accrues, under O.C.G.A. § 9-3-33, unless another law provides otherwise; claims for injury to reputation have one year, and injury claims involving loss of consortium have four years.
Is a life care plan the same as medical bills?
No. Bills show care already received. A life care plan projects care that will still be needed.
Can a life care plan be challenged?
Yes. Georgia law allows evidence challenging the reasonableness and medical necessity of projected medical expenses.
If you’re weighing what a serious injury may cost over the coming years, our team at Slam Dunk Attorney in Duluth, Georgia can review your situation with you. Responsible lawyer Peter F. Jaraysi and our team can talk through the medical picture and the questions a life care plan raises. The initial consultation is free, confidential, and without obligation to continue. Contact Slam Dunk Attorney to start that conversation.
What a Life Care Plan Can Cover
Medical and surgical care
Ongoing doctor visits, procedures, medications and follow-up treatment that a serious injury may require over time.
Daily and attendant care
Help with bathing, dressing, meals, transportation and other tasks that change after a catastrophic injury.
Equipment and home changes
Wheelchairs, mobility aids, prosthetics, and modifications such as ramps, widened doorways or accessible bathrooms.
Organized records
A clear, well-documented picture of your needs that can be shared with doctors, therapists and your legal team.
Start Documenting Now
Keep copies of medical records, bills, receipts, prescriptions and mileage to appointments. Write down daily limitations, pain and tasks you can no longer do on your own. Clear, detailed records make it easier to describe your needs accurately.
How Our Team Can Help
Talk with us
Share what happened and what your daily life looks like now. We listen, answer your questions and explain your options in plain language.
Gather your records
We help collect medical records, bills and other documents that show the care you have needed and the care you may need in the future.
Map your future needs
We work with your medical providers to understand the treatment, therapy and support that may be needed over time.
Plan your next steps
We explain how a life care plan fits into your case and keep you informed at every stage, so you always know what comes next.